Quick answer
Bunbury businesses can borrow from banks, non-bank lenders, equipment financiers and private lenders. Lenders here look hard at customer concentration, because much of the local economy supplies the port, the alumina refineries and the lithium sector. WA payroll tax starts above $1m in annual wages, and owners with property can use a caveat or second mortgage loan secured through Landgate when speed matters.
Key points
- The Port of Bunbury moves alumina, grain, spodumene, woodchips and more than a dozen other commodities, and its suppliers borrow on the strength of those contracts
- Albemarle idled the last operating train at its Kemerton lithium hydroxide plant in February 2026, so lenders now ask South West contractors how much work depends on one site
- WA payroll tax applies above $1m in wages, with the deduction tapering away by $7.5m
- On a WA title, an owner can give a caveator 21 days' notice to get a court order or lose the caveat
- Land registry
- Landgate
- Payroll tax threshold
- $1m annual WA wages (2025–26)
- Dispute help
- Small Business Development Corporation
- Enquiry range
- $5k to $5m, business purposes only
In February 2026 Albemarle announced it would idle Train 1, the last operating line at its Kemerton lithium hydroxide plant north of Bunbury, two years after putting Train 2 into care and maintenance. For the fabricators, electricians, labour hire firms and caterers around Australind and Picton who had built their books around that site, the news was a reminder of how Bunbury’s economy works. Big industrial customers bring steady, well-paid work, until they don’t.
That’s the lens most lenders bring to a South West application. It’s not a reason to expect a no. It’s a reason to show them, clearly, where your money comes from.
We don’t have an office in Bunbury, Busselton or anywhere else. Everything happens by phone and online, and we cover the whole of Western Australia the same way.
What does the Bunbury economy actually run on?
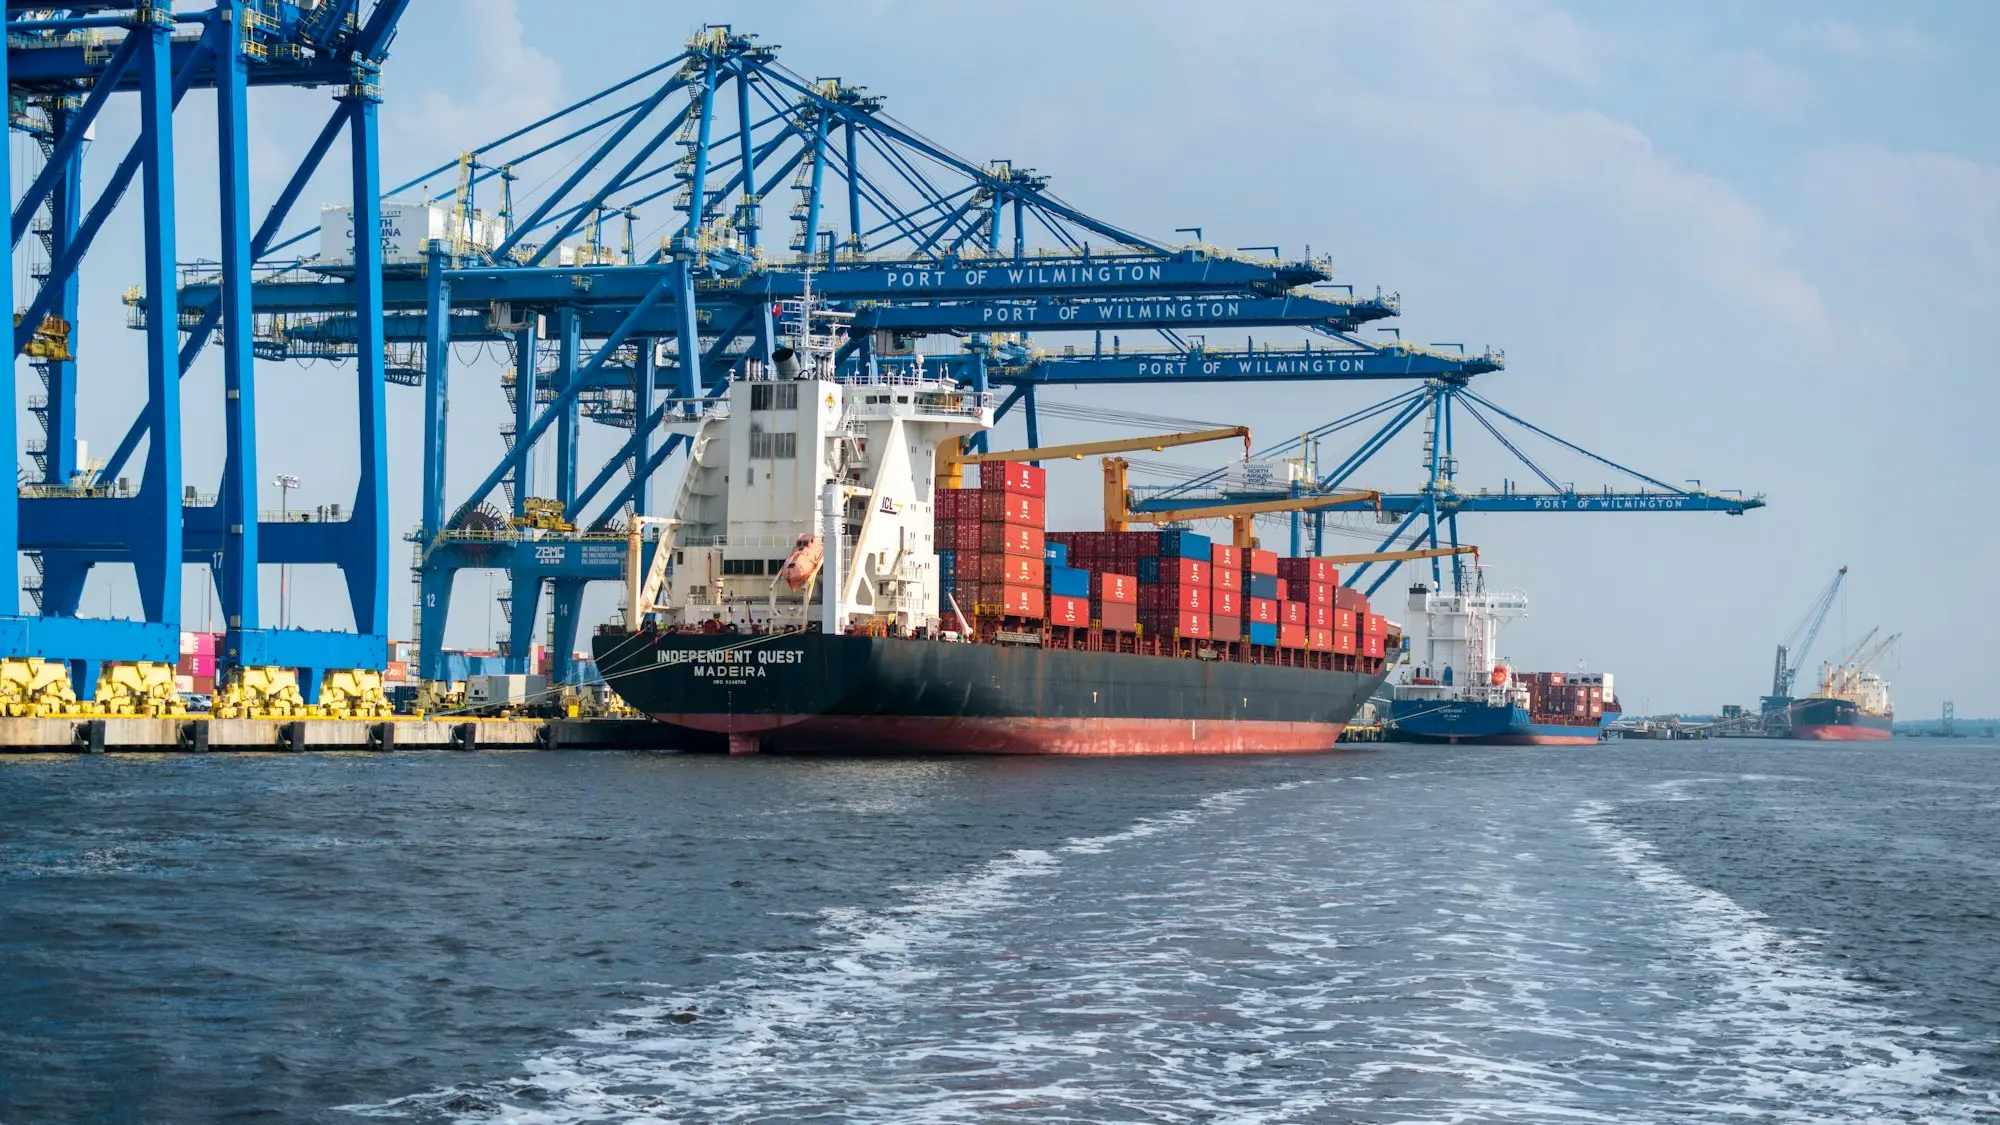
The port is the clearest place to start. Southern Ports reports that the Port of Bunbury handles about 16.9 million tonnes of trade across more than 15 commodities, through seven berths, and describes it as the world’s largest lithium export port. Alumina from the refineries inland is the biggest volume, alongside grain, spodumene, caustic soda, woodchips, mineral and silica sands, copper concentrate, coal, fertiliser and fuel.
Around that sit the businesses that actually apply for loans:
- Industrial services. Maintenance, fabrication, electrical and civil contractors in Kemerton, Picton and Davenport working for refineries, the port and processing plants.
- Transport. Road trains and tippers carting grain, timber, sands and industrial inputs to and from the wharf. See our page on trucking companies.
- Energy transition work. Collie’s coal-fired power stations are winding down, and the port now offers laydown space for wind turbine components and batteries.
- Agriculture, timber and wine. Dairy and beef on the coastal plain, plantation timber, and the vineyards that run south towards Margaret River.
- Town and tourism. Health, education, retail, hospitality, and the holiday trade that swells every summer along Koombana Bay and Geographe Bay.
How do lenders read a contractor-heavy region?
When a lender reads a Bunbury industrial services business, the first thing it checks is often concentration: what share of revenue comes from the top one or two customers. Above roughly half, most credit teams want to understand what happens if that customer stops.
You can get ahead of that:
- List your customers and contract end dates. A one-page schedule is more persuasive than a bundle of invoices.
- Separate one-off work from recurring work. Shutdown and turnaround jobs are lucrative but lumpy. Lenders prefer to size repayments on the base you can rely on.
- Explain any drop. If a site like Kemerton fell away, show what replaced the work, even if margins are thinner for now.
- Keep the tax side clean. Overdue BAS or a missed ATO payment plan instalment worries a lender more than a lumpy month does. Our page on ATO tax debt business loans explains how lenders treat it.
If you’ve just landed a large contract and need to pay wages and buy steel well ahead of being paid, the options are different again. Won a big contract and need to fund it walks through invoice finance, equipment finance and short-term facilities for exactly that gap.
WA payroll tax: what a growing South West employer pays
Western Australia’s payroll tax threshold is $1m in annual taxable wages for 2025–26. Above that, the deduction shrinks by a tapering formula and disappears entirely once wages reach $7.5m, and tax is charged on wages above the remaining deduction.
The WA Government’s own worked example shows the scale. An employer with $1.2m in WA wages keeps a deductible amount of about $969k and pays around $12.7k a year in payroll tax. Contractors who hire quickly for a shutdown season can cross the threshold without noticing, so watch it month by month rather than at year end.
For a lender, payroll tax is a fixed cost that comes off profit before any loan repayment is counted. If you’re about to cross the threshold, run your numbers through the business borrowing power calculator with the new cost included.
Need a quick read on your options? Outline what you need on our enquiry form. It’s a minute’s work and it doesn’t trigger a credit check.
Borrowing against property: the Landgate side
Landgate holds the register for every Western Australian title, and lenders lodge caveats and mortgages electronically. That’s what lets a caveat loan settle in days rather than weeks. The detail many owners don’t know concerns removal. According to Landgate’s caveat removal guide (version 18, February 2026), the registered owner can apply under section 138B. Once notice is served, the caveator gets 21 days to come back with a Supreme Court order keeping the caveat alive; without one, Landgate removes it. Separate 14-day notice procedures apply in some other situations.
For a borrower, that cuts both ways. A properly documented loan caveat, lodged with your consent and withdrawn when you repay, is routine. An old or disputed caveat on your title is something to clear before you apply, because a refinancing lender will see it on the first title search.
If you’d rather a registered mortgage behind your existing home loan, weigh up a second mortgage business loan against the caveat route. Our caveat loans in Perth page covers the WA practicalities in more detail.
Banks first, then the alternatives
WA’s banks and regional lenders are usually the cheapest source of business money, and an approval from one of them is worth taking seriously. They’ll typically want two years of financials, clean tax lodgements and a business that isn’t overly reliant on one customer.
When a Bunbury business doesn’t fit that shape, these are the usual next steps:
- Equipment finance for trucks, plant, elevated work platforms and workshop machinery. The asset secures the loan.
- Invoice finance for contractors paid on 30 to 60 day terms by large industrial customers.
- Property-secured loans from non-bank and private lenders, using your home or an industrial unit. Our own brands HomeSec Business Finance and EquityTap specialise in lending against property.
- Unsecured business loans for smaller, short-term needs, assessed on trading history and bank statements.
If there’s a dispute behind your cash shortfall, such as an unpaid invoice from a larger company, the Small Business Development Corporation runs a low-cost dispute resolution service and lists regional support for the South West.
A worked example: rebuilding after a lost contract
A hypothetical scenario.
A steel fabrication business in Kemerton earned about 60% of its revenue from maintenance work at a lithium processing site. When that work stopped, turnover fell sharply for two months before new jobs from the port and an alumina refinery came in. Those new customers pay on 45-day terms.
The owner had $85k of overdue supplier accounts and a quarterly BAS due. Their bank, looking at the two weak months, declined an overdraft increase.
The owner sent three months of statements showing the recovery, a schedule of new purchase orders, and details of their house in Eaton. A private lender approved a six-month second mortgage, sized to clear the suppliers and the BAS, with a plan to refinance to the bank once six clean months were on record. Separately, an invoice finance facility on the new refinery work smoothed out the 45-day wait.
Ready to talk about your South West business?
Bunbury rewards businesses that can ride an industrial cycle. Sometimes that takes a bit of borrowed time.
If that’s where you are, the enquiry form gets you a realistic answer without a week of phone tag. Set aside a minute, and know that nothing about it shows up as a credit enquiry. Your details aren’t fired off to dozens of finance companies. Someone on our team goes through your contracts, your security and your timing and phones you to discuss it. Accurate figures save us all a round of back-and-forth and point us straight at the right fit.
Frequently asked questions
Will a lender hold the Kemerton shutdown against my Bunbury business?
Not if your income doesn't depend on it. Lenders look at your own customers and statements. If Kemerton work was a large share of your revenue, expect questions about what has replaced it, and have your current contracts and the last three months of statements ready to show the new mix.
Can I get equipment finance as a mining or port contractor in Bunbury?
Yes. Equipment financiers lend against machinery, trucks and plant across the South West, and the asset itself is the main security. Newer contractors may need a bigger deposit or a guarantor, and some financiers want to see the contract the equipment will be used on.
How long does a caveat loan take in Western Australia?
Once the lender has approved the deal and you've signed, the caveat can usually be lodged electronically with Landgate within a day or two. Most of the time goes into the lender checking the property's value and your exit plan, so having a recent rates notice and loan statements ready helps.
Does the SBDC lend money to small businesses?
No. The Small Business Development Corporation is a WA Government agency offering free advice, workshops and a low-cost dispute resolution service. It can help with a payment dispute or a lease problem, but funding still comes from banks and other lenders.
Is Bunbury business property easy to borrow against?
Houses in Bunbury, Australind and Dalyellup are generally straightforward security for most lenders. Industrial units around Picton and Davenport are accepted by many commercial and private lenders, usually at a lower share of value than a home. Specialised buildings can take longer to value.