Quick answer
Ballarat businesses can borrow from banks, non-banks, fintechs and private lenders, secured or unsecured, and almost always online. Three local factors shape a deal: many central commercial buildings sit under heritage controls that affect valuations and works, the 438-hectare Ballarat West Employment Zone is drawing industrial growth, and the visitor economy is strongly seasonal. Eligible employers also pay Victoria's regional payroll tax rate.
Key points
- Health, education, advanced manufacturing and the visitor economy are the city's key sectors, with names like McCain, Mars Wrigley and Alstom in manufacturing
- Heritage controls on a commercial building can lower a valuation and raise renovation costs, so lenders check before they commit
- The Ballarat West Employment Zone, beside the airport, is where many growing firms build or buy, which brings land and construction finance into play
- Ballarat counts as regional Victoria, so eligible employers get the 1.2125% regional payroll tax rate instead of 4.85%
- Land registry
- Land Use Victoria
- Key growth precinct
- Ballarat West Employment Zone (438 ha)
- Dispute help
- Victorian Small Business Commission
- Enquiry range
- $5k to $5m, business purposes only
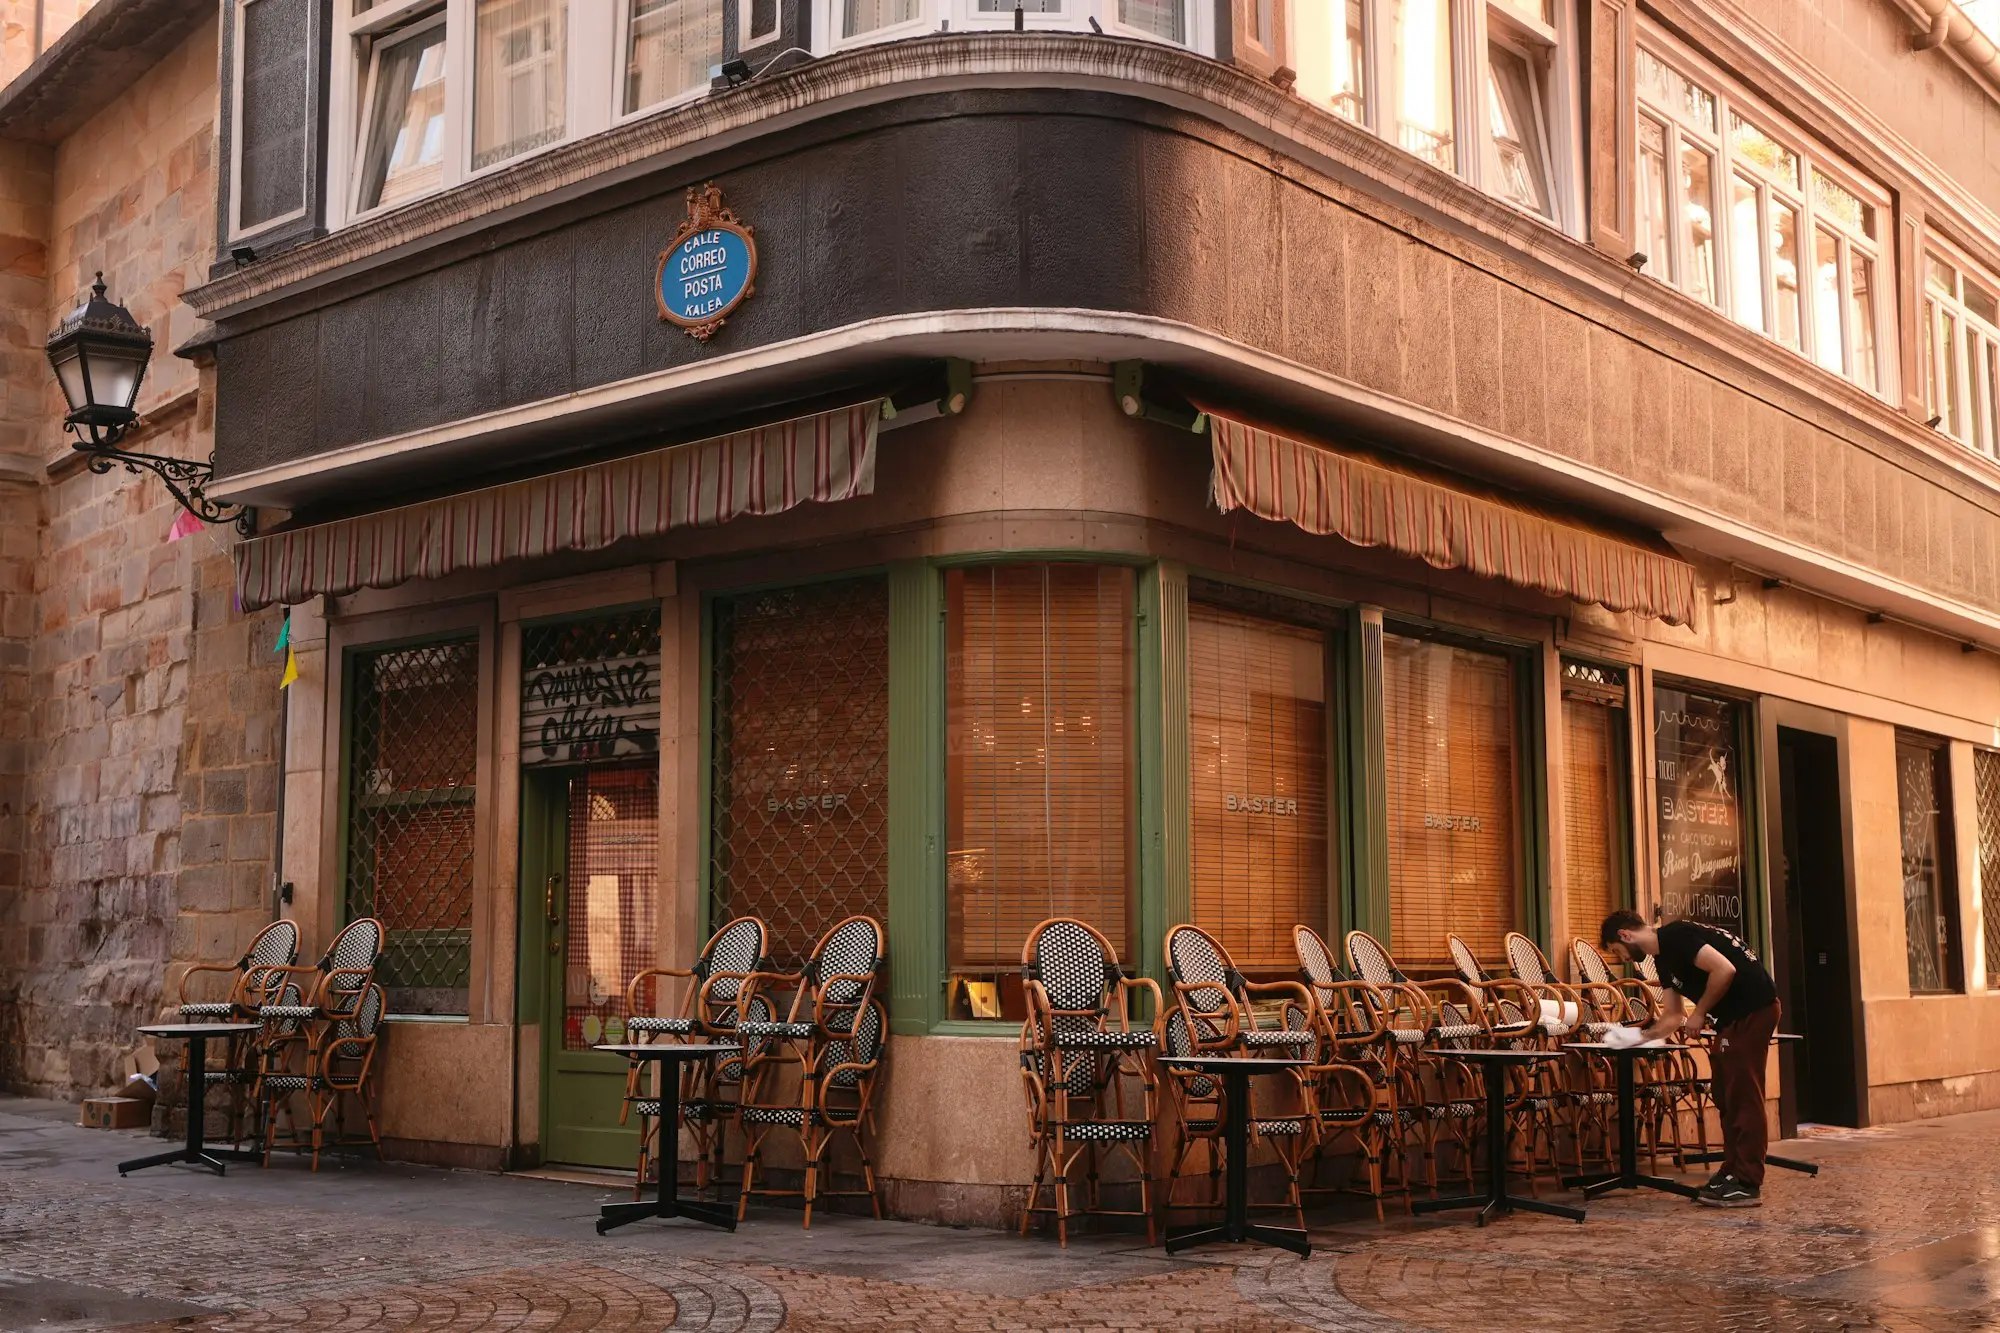
Walk down Lydiard Street or Sturt Street and you’re surrounded by gold-rush wealth turned into stone: banks, hotels and shopfronts built in the 1800s and still trading. That heritage is a big reason around four million people visit Ballarat each year, according to the city’s investment arm. It’s also something a lender will notice the moment you offer one of those buildings as security.
Ballarat’s economy has moved well beyond tourism, though. The city lists health, education, advanced manufacturing and the visitor economy as its key sectors, with Federation University, McCain Foods, Mars Wrigley, PETstock and Alstom’s train works among the names behind them. Below is how that shapes borrowing locally. We’re a national service with no Ballarat office; everything happens by phone and online.
Why does a heritage building change the loan?
A heritage overlay or a listing on the Victorian Heritage Register doesn’t stop you borrowing. It does change three things a lender cares about:
- The valuation. A valuer considers what can and can’t be done with the site. Limits on demolition, extensions or façade changes can narrow the pool of future buyers, and a lower valuation means a smaller loan for the same deposit.
- The cost of works. Planning permits are generally needed for external changes, and repairs often call for specialist trades and materials. If you’re borrowing for a fit-out, build a contingency into the amount.
- Insurance. Rebuilding an old masonry building to its original standard costs more, and lenders will want the property properly insured before settlement.
None of this is a deal breaker. It just means a bit more paperwork up front. Have a building inspection report, the title search and any existing permits ready before you apply, and expect the lender to order a full valuation rather than a desktop one. Our guide to how lenders value commercial property explains the method.
Growing into the Ballarat West Employment Zone
The Ballarat West Employment Zone (BWEZ) covers 438 hectares beside Ballarat Airport, built in stages on surplus Crown land, with a freight hub and road and rail access. The council sees it as the city’s main engine for new jobs over the next two decades.
For a business outgrowing a leased shed in Wendouree or Delacombe, moving there raises a set of funding choices:
| Path | How it’s usually funded | Points to consider |
|---|---|---|
| Lease a new building from a developer | Fit-out and equipment finance only | Lowest upfront cost, but no equity builds up |
| Buy land, then build | Land loan, then staged construction finance | Lenders want plans, a fixed-price contract and a contingency |
| Buy a completed building | Commercial property loan | Check whether the property has entered Victoria’s CIPT regime, which affects stamp duty |
| Sell your old premises and lease back | Sale and leaseback | Frees capital for machinery or stock |
Banks are often at their best for a planned, owner-occupied build with solid financials, so start there. Where a non-bank or private lender usually helps is the deposit or a timing gap, for instance borrowing against your home until the old building sells. The bridging loan calculator shows what that bridge costs in dollars.
The visitor calendar and the cold months
Sovereign Hill, the galleries, events and school holidays bring waves of visitors, while a Ballarat July can be bleak for foot traffic. Hospitality and retail owners often see takings swing sharply between peaks and troughs.
Lenders reading your bank statements will see those swings. Help them by showing the full 12-month pattern and explaining it in a sentence or two. Products that cope well with seasonality include:
- A business line of credit drawn down in the quiet weeks and repaid from busy ones.
- A short-term loan timed to stock up before a peak, cleared once trade lifts.
- An equity-backed loan for a winter refurbishment, so the venue is ready when visitors return.
Quiet month ahead and bills that won’t wait? Send us a quick enquiry. It’s a minute’s work and doesn’t trigger a credit check.
Payroll tax for growing Ballarat employers
Victoria’s payroll tax threshold is $1m in annual wages. Above that, eligible regional employers pay 1.2125% rather than the 4.85% standard rate, provided at least 85% of Victorian taxable wages go to staff who mostly work in regional Victoria. Ballarat qualifies as regional.
For a manufacturer hiring its way past $1m in wages, that’s a meaningful saving, and a lender modelling your repayments should use the lower rate if you’re eligible. Make sure your accountant’s forecasts reflect it. The business borrowing power calculator is a handy way to test the numbers yourself.
A Ballarat example
Invented numbers, used only to illustrate the thinking.
The owners of a successful restaurant want to buy the two-storey Victorian building they’ve leased on Sturt Street for eight years. The price is $1.45m. The bank’s valuer, mindful of the heritage controls and an upstairs floor that needs work, comes in at $1.3m. At the bank’s loan-to-value limit, that leaves the owners about $150k short of what they’d planned.
Rather than lose the building to another buyer, they look at a second mortgage business loan over their home in Alfredton to cover the gap, with a plan to refinance it into the bank facility after two years of rental income from the restored upstairs. They price both options on the loan cost comparison calculator before committing.
Start with the bank, and keep going if it says no
Banks and local credit unions are frequently the cheapest finance in Ballarat, and if one of them approves you on sensible terms, give that offer real weight.
Where banks struggle is with tight deadlines, newer businesses, heritage properties that value awkwardly and income that rises and falls with the seasons. If your bank has declined you, our pages on bank alternatives and seasonal businesses set out where to look next. Owners working across central Victoria may also find our Bendigo page useful.
Let’s look at your Ballarat plans together
From a heritage shopfront in the CBD to a new factory out at BWEZ, the right finance depends on what you’re offering as security, how your income moves through the year and what the money will do.
When you’re ready, our enquiry form asks for just the basics and takes roughly a minute. Your credit score isn’t touched when you submit it. We don’t pass your enquiry around the market, so your mobile stays quiet. A real member of our team studies the detail of your situation and rings you personally. Give us honest, accurate figures and we can match you with a suitable lender sooner, without false starts.
Frequently asked questions
Will a lender accept a heritage-listed building in Ballarat as security?
Generally yes, but expect more questions. The valuer will consider how heritage controls limit redevelopment and alterations, and that can mean a lower value or a lower maximum loan-to-value ratio. A clear building report and any existing permits help the process.
How do I fund a new building in the Ballarat West Employment Zone?
Usually with a land purchase loan followed by construction finance drawn in stages, or a single development facility. Some businesses use equity in their current premises or home to cover the deposit. Banks are often the cheapest option for a well-planned owner-occupied build.
Is Ballarat regional Victoria for payroll tax purposes?
Yes. Employers who pay at least 85% of their Victorian taxable wages to regional employees can use the regional rate of 1.2125%. The Victorian threshold is $1m in annual wages from 1 July 2025.
My Ballarat café is quiet in winter. Can I still borrow?
Yes. Lenders who understand seasonal trade look at a full 12 months of bank statements rather than one bad month. A line of credit or flexible repayments often suits a business that is busy around school holidays and events but quiet in the cold months.
Do I need to visit a lender in Melbourne?
No. Applications, identity checks and signing are done online for most business loans, and property valuations in Ballarat are carried out by local valuers on the lender's panel.