Quick answer
Newcastle businesses can borrow from banks, non-bank lenders, fintechs and private lenders, unsecured on turnover or secured against property. Lenders pay close attention to customer concentration, because so much local work traces back to coal, the port, heavy industry and defence. Health, education and services make the city more diverse than it was. NSW rules apply: electronic title dealings, a 21-day lapsing notice process for caveats and payroll tax above $1.2m.
Key points
- Lenders look hard at who your customers are; heavy reliance on one mine, smelter or prime contractor narrows your options
- Big local anchors gained certainty recently: Tomago's power deal runs to 2038 and the airport's new terminal opened in 2025
- Health, education and professional services now spread Newcastle's risk across far more than coal and steel
- NSW title dealings are fully electronic, and NSW payroll tax starts above $1.2m in annual wages
- Land registry
- NSW Land Registry Services
- Payroll tax threshold
- $1.2m annual wages
- Dispute help
- NSW Small Business Commission
- Enquiry range
- $5k to $5m, business purposes only
There’s one question a credit assessor almost always asks a Newcastle business, even if it isn’t phrased this way: if the big customer stopped calling, what would be left? In a city built on coal exports, steel and heavy engineering, that’s a fair question. It’s also one Newcastle businesses are increasingly well placed to answer, because the city’s economy now leans just as much on hospitals, the university, defence, construction and services.
This guide focuses on what a lender sees when it looks at a Newcastle application, from the Honeysuckle waterfront to the industrial estates at Beresfield and Kooragang. Our team works nationally and doesn’t have a Newcastle office, so the whole process runs over the phone and online.
How do lenders read a Newcastle business?
Most lenders run the same core checks everywhere: trading history, bank statements, tax compliance, security and the purpose of the loan. In Newcastle, three extra questions come up far more often than in other regional cities.
Who are your customers? Engineering shops, labour hire firms, transport operators and maintenance contractors often earn most of their income from a handful of mines, the port or one industrial plant. A lender will want to see your top five clients, what slice of turnover each represents and when each contract is due for renewal.
How long are your payment terms? Large industrial and government clients can pay on 30 to 60 days or longer. That’s not a problem if you can fund the gap, and it’s often the reason a business needs finance in the first place.
Is your sector growing or shrinking? Coal still makes up the great bulk of the tonnage through the Port of Newcastle, and the port has publicly aimed to grow non-coal trade. Lenders take a longer view than one contract, so it helps to show how your business would cope if your main sector slowed.
The anchors: port, smelter, airport and air base
A handful of big operations sit behind a lot of Newcastle supply chains, and their prospects ripple through to local subcontractors.
| Anchor | Recent news | What it means for local businesses |
|---|---|---|
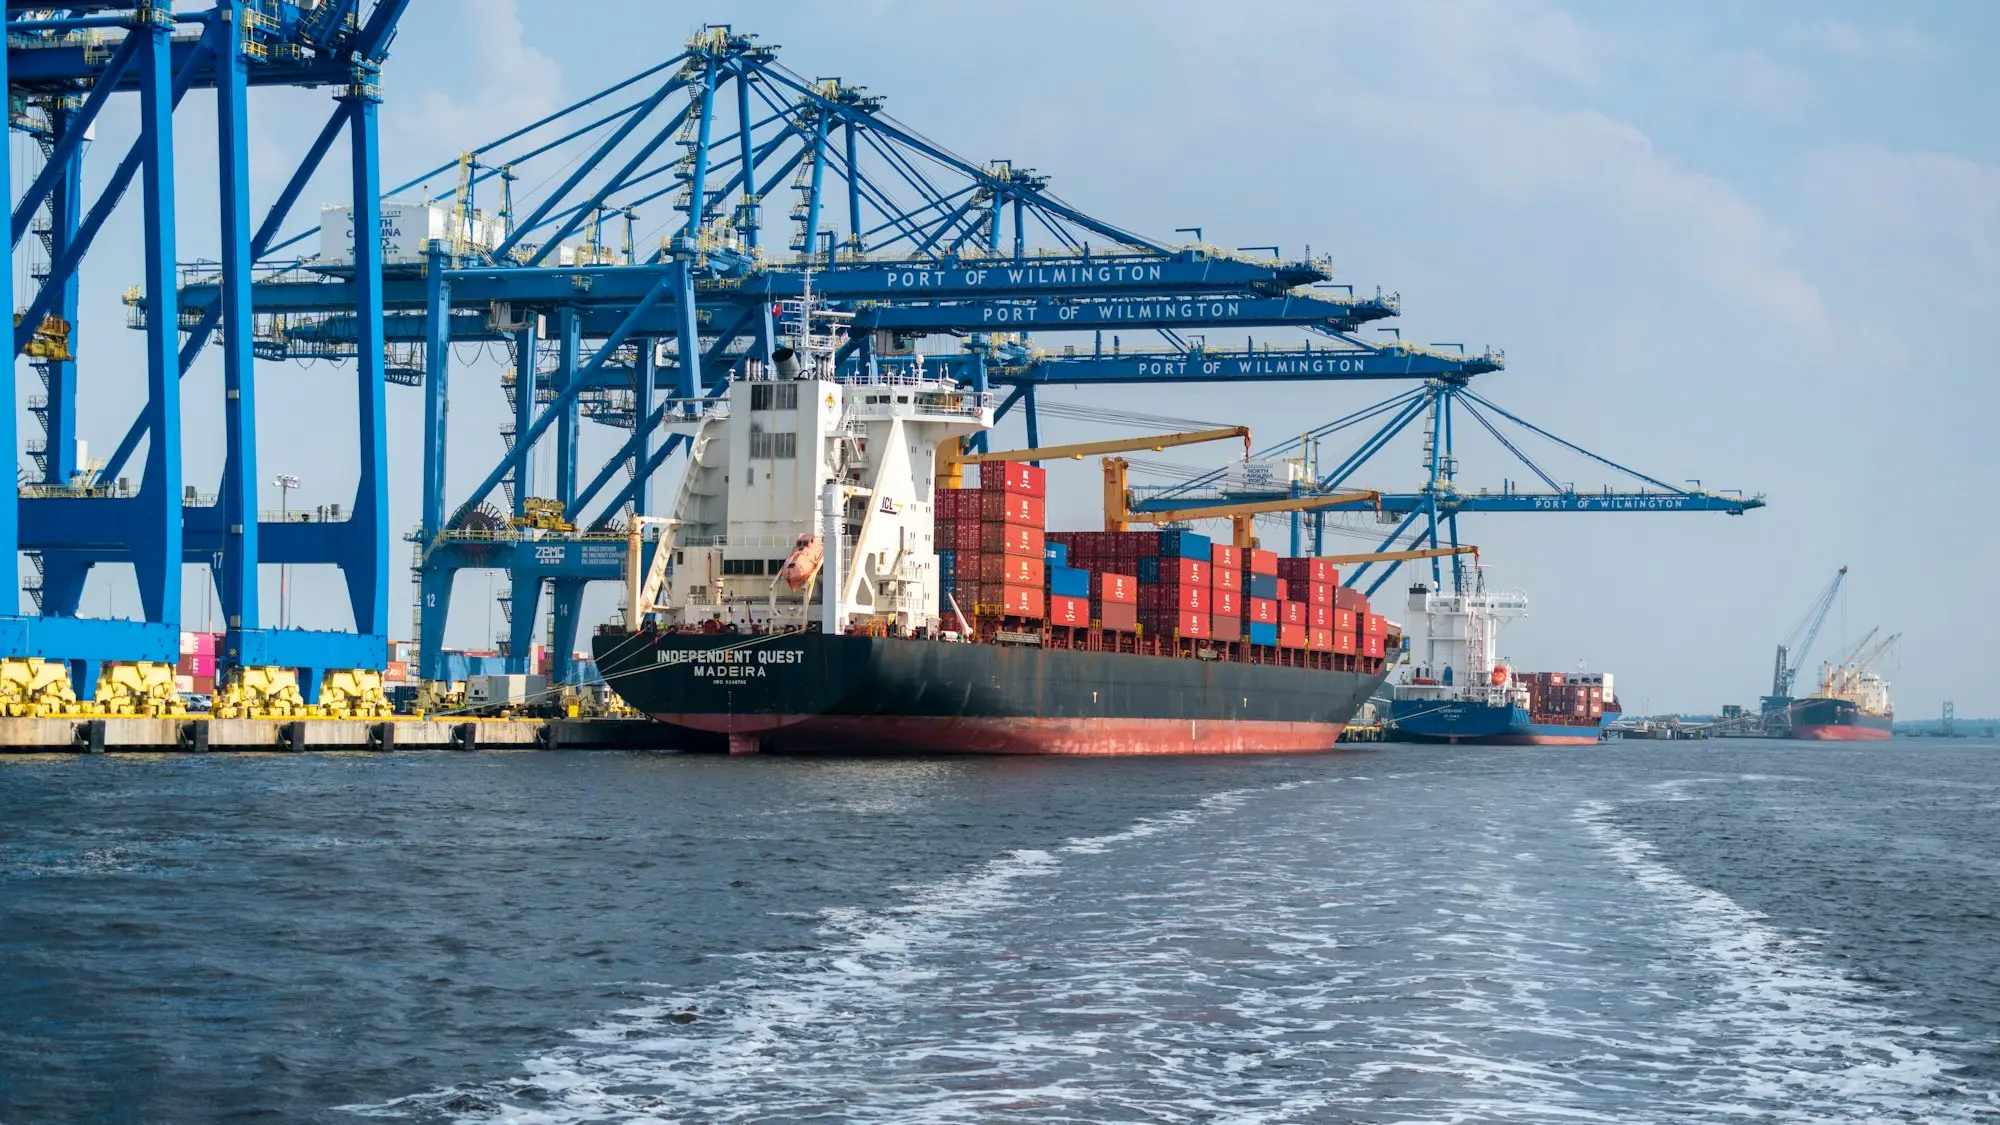
| Port of Newcastle | Still dominated by coal, with plans to diversify into containers and clean energy | Steady maintenance and logistics work, with a long-term shift in the kind of work on offer |
| Tomago Aluminium | In August 2026 Rio Tinto announced an agreement with the federal and NSW governments securing power through to 2038 | Removes a major cloud over suppliers and contractors who rely on the smelter |
| Newcastle Airport | New terminal officially opened in September 2025, with more gates and capacity | More visitors, more freight potential and more hospitality demand |
| RAAF Base Williamtown | Home to F-35A squadrons and a cluster of defence and aerospace businesses | Reliable but compliance-heavy subcontracting with long payment chains |
None of these guarantees anything for an individual business. But when you can show a lender that your work connects to an anchor with a secure future, you’ve answered the concentration question before it’s asked.
A diversifying city: health, education and services
Newcastle’s economy has broadened considerably. John Hunter Hospital and the surrounding health services are among the region’s largest employers, the University of Newcastle anchors education and research, and the NSW Government’s Hunter Regional Plan describes Greater Newcastle as offering metropolitan-level health, education and research facilities. Newcastle West and the Honeysuckle waterfront now house professional firms that once would have been in Sydney.
That matters for lending. A medical practice, an engineering consultancy or an accounting firm in Newcastle is assessed much like its Sydney equivalent: steady income, low physical assets and mostly unsecured borrowing based on cash flow. Hospitality along Darby Street, Beaumont Street in Hamilton and the foreshore is more seasonal and event-driven, and is assessed on a full year of statements.
Funding the long payment chain
For Newcastle’s industrial businesses, the most common problem isn’t profit. It’s timing. A fabrication shop in Cardiff might finish a $200k job for a mine operator in March and not see the money until May, while wages and steel are paid weekly.
The tools that fit that pattern:
- Invoice finance: advance most of each approved invoice as you raise it, so you’re paid closer to when you do the work.
- Equipment finance: buy cranes, CNC machines, trucks or service vehicles without draining working capital.
- A secured line of credit: a standing buffer against property, drawn when a big client pays late.
To see whether a new loan fits your cash flow, test it with the debt service coverage ratio calculator. Lenders run the same sort of maths.
Waiting on a large client and need to cover wages? Put the numbers in our quick form. It’s around sixty seconds of work and makes no enquiry on your credit file.
NSW rules that apply in Newcastle
Newcastle sits under the same state rules as Sydney, which keeps secured lending simple.
Electronic title dealings. All NSW land dealings, including mortgages and caveats, are lodged electronically with NSW Land Registry Services. Old paper titles have been redundant since late 2021. The slow parts of a secured loan are the valuation and the paperwork, not the lodgement.
Caveats and lapsing notices. If someone wants a caveat removed, they can apply for a lapsing notice, after which the caveator generally has 21 days to get a Supreme Court extension order or the caveat lapses. A properly documented caveat loan is withdrawn by the lender as soon as you repay, so it rarely gets that far.
Payroll tax. Revenue NSW charges payroll tax once annual wages exceed $1.2m. A growing engineering or labour hire business can cross that line quickly with a few extra hires, and lenders check that payroll tax, BAS and super are current.
Dispute help. For lease or contract fights, the NSW Small Business Commission runs a mediation service at modest cost, which can be worth trying before borrowing to resolve a disagreement.
Example: a Cardiff engineering firm
A hypothetical example, not a client story.
An engineering and fabrication business in Cardiff turns over $5.5m, with about 70% of revenue from maintenance contracts at two Hunter Valley mines. It has just been accepted onto a supplier panel for a defence prime at Williamtown and been offered its first package: $350k of fabricated components over four months, paid on 45-day terms.
The director wants to take it on, partly because it reduces dependence on coal. The business needs $60k of new tooling and about $150k of working capital to carry the job until the first payment.
Its bank is supportive of the defence diversification but wants to restructure existing facilities first, a process likely to run about six weeks, and the defence job starts sooner. A practical structure might be invoice finance across both the mine and defence debtor books, freeing up cash from existing invoices immediately, plus equipment finance for the tooling. Once the bank’s review is done, the director can revisit whether a cheaper bank facility should take over.
Banks first, then options if they decline
The major banks and the region’s own customer-owned banks are active business lenders across Newcastle and the Hunter, and when you fit their criteria they’re often the cheapest route. Take any reasonable offer seriously.
If the bank is too slow, wants more security than you have, or isn’t comfortable with your customer concentration, there are other paths. The declined by the bank page explains them, and our Hunter Valley guide covers borrowing for businesses closer to the mines and vineyards.
Newcastle business, national reach: start your enquiry
Whether you’re fabricating for the port, staffing a hospital contract or opening a second venue in Hamilton, three answers decide most applications: the purpose, the repayment source and the security behind it. You can tell us all three in a minute.
Filling in our form doesn’t run a credit check, so there’s no risk in asking. We work your enquiry ourselves and don’t sell it on to a string of lenders, which keeps the calls to the one that matters. An experienced person reads the details and phones you to talk them through. Please be accurate with turnover, security and timing; it’s how we find the right match without wasting your week.
Frequently asked questions
Will lenders worry that my Newcastle business depends on the coal industry?
They'll ask about it. Lenders look at how much of your revenue comes from one customer or one sector and how long your contracts run. Heavy reliance on coal doesn't rule you out, but showing a spread of clients, long-term agreements or work in other sectors improves your options.
Can I use my Newcastle home as security for a business loan?
Yes. Lenders can register a first or second mortgage, or a caveat, over a Newcastle or Lake Macquarie home. NSW dealings are lodged electronically, so once the valuation and documents are complete, the security itself is quick to put in place.
How do caveats get removed in NSW?
A property owner or other interested party can apply for a lapsing notice. Once it's served, the caveator generally has 21 days to obtain a Supreme Court order extending the caveat, otherwise it lapses. Loan caveats are normally withdrawn by the lender when the loan is repaid.
Is defence work at Williamtown good for getting finance?
Defence contracts are usually seen as reliable income, which helps. The catch is long payment terms and strict compliance costs for subcontractors, so lenders often suggest invoice finance or a working capital line rather than a lump-sum loan.
Does the NSW Small Business Commission lend money?
No. It helps small businesses resolve disputes with landlords, suppliers and other businesses through low-cost mediation. Fixing a dispute can sometimes remove the problem a loan was meant to solve.