MyState Bank
BankHobart
- What they fund
- Secured loans
- Website
- mystate.com.au
- In a sentence
- Tasmanian bank.
Quick answer
MyState Bank is a Hobart-based bank owned by ASX-listed MyState Limited. As at October 2026, its own website offers business transaction and savings accounts but doesn't list business loans. The group's business lending runs through Selfco, a division of MyState Bank that has financed vehicles, equipment and machinery for business since 2003, and which takes applications nationally through accredited finance brokers.
Key points
- MyState Bank's website, as at October 2026, lists business deposit and transaction accounts but no business loans or overdrafts
- The Everyday Business account is only available to businesses based in Tasmania
- Selfco, a division of MyState Bank since well before the 2025 Auswide merger, finances business vehicles, equipment and machinery through brokers nationwide
- Selfco's lending grew 134% to $371m in the 2026 financial year, so it's an active, growing lender
- For an unsecured loan, an overdraft or property-backed business funding, you'll need a different lender
- Lender type
- Listed regional bank
- Based
- Hobart
- Business lending
- Vehicle and equipment finance through Selfco
- How to apply
- Selfco works through accredited brokers
Plenty of Tasmanian owners bank with MyState, and for good reason: it’s a home-grown bank with branches across the state and a reputation for looking after its customers. So when the business needs money, it’s natural to ask MyState first.
Here’s the honest answer as at October 2026. MyState Bank’s own website doesn’t list a business loan, overdraft or line of credit. What it does offer is business transaction and savings accounts, and, through a division called Selfco, finance for business vehicles, equipment and machinery. This page explains how that works, who it helps, and where to go for the kinds of business funding MyState doesn’t advertise. Check current details with MyState or Selfco before acting.
What does MyState Bank offer business customers?
MyState’s business section is about banking rather than borrowing. As at October 2026 it lists:
| Product | What it’s for | Worth knowing |
|---|---|---|
| Everyday Business account | Day-to-day transactions | Only for businesses based in Tasmania; a modest monthly fee with an allowance of free transactions |
| Business Online Saver | Holding spare cash | Separate from your trading account |
| Business Term Deposits | Locking away funds for a set term | Useful for tax and GST set-asides |
MyState Limited also owns Auswide Bank, which it acquired in February 2025, and the wealth business TPT Wealth. Auswide’s business offering likewise centres on accounts and merchant services rather than published business loans.
So where does the business lending happen?
At Selfco. Selfco has been financing business assets since 2003 and describes itself as a division of MyState Bank Limited. It funds the purchase of equipment, machinery and vehicles used in a business, across a wide range of client types and asset classes.
Three things set it apart from a typical bank product:
It works through brokers, not branches. Selfco originates loans nationally through accredited finance brokers and is on the panels of most broker aggregation groups. You won’t apply for it at a MyState counter. If you already use a broker for equipment, ask whether Selfco is on their list. Our guide to brokers versus going direct explains the trade-offs.
It lends Australia-wide. Unlike MyState’s Tasmania-only business account, Selfco has sales staff covering the eastern seaboard capitals and Western Australia.
It’s growing quickly. Industry reporting in August 2026 put Selfco’s lending growth at 134% for the 2026 financial year, reaching $371m. A lender that’s expanding its book is usually keen to see good-quality deals.
Selfco doesn’t publish amounts, terms or eligibility criteria on its website, so the detail comes through your broker. Our Selfco lender profile tracks what’s known about it.
How does equipment finance through Selfco usually work?
Equipment finance is secured on the asset itself, so you generally don’t need property as security. Businesses buying outright most often use a chattel mortgage, where the title is yours at settlement and the financier registers its interest against the machine. Leases and hire purchase are alternatives with different tax treatment, so talk to your accountant.
Before your broker sends anything to Selfco, it helps to know:
- the make, model and year of the asset, plus the supplier’s quote;
- your ABN and GST registration dates;
- your latest few months of trading account statements, with financials ready if the deal is large;
- whether you want a balloon payment at the end and how big.
Our equipment finance calculator gives you a ballpark repayment figure in a couple of minutes.
A worked example
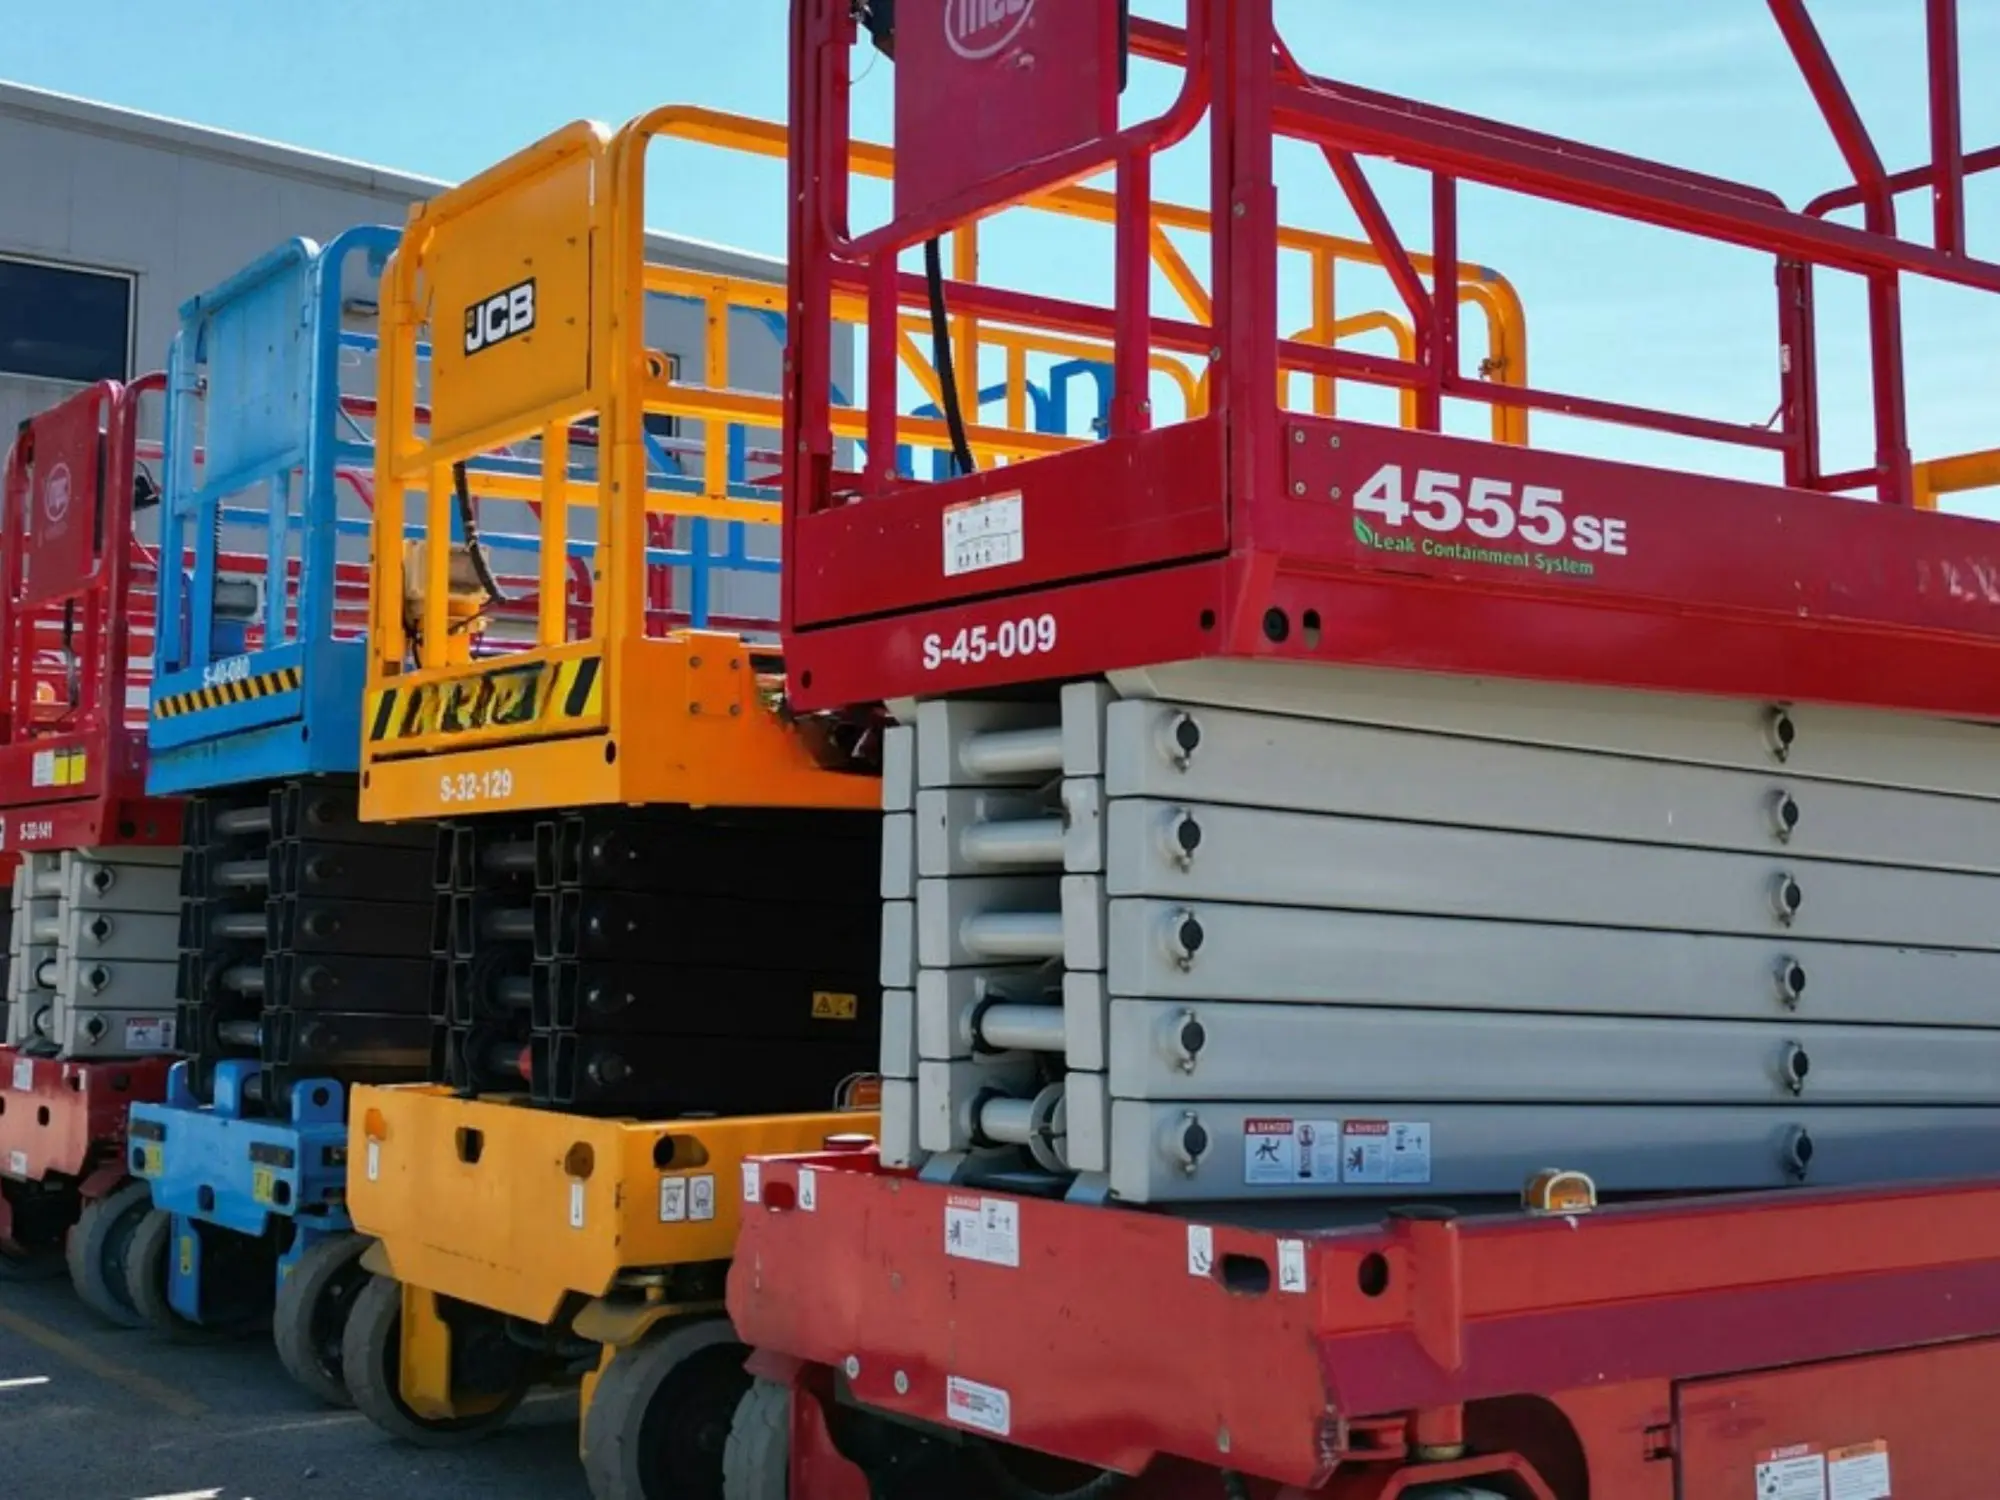
Imagine an illustrative Launceston access hire business, three years trading, banking with MyState. A large construction contract means the owner needs two more scissor lifts and $60k of working capital to cover wages until the builder’s first progress payment.
The scissor lifts are a natural Selfco deal: hard assets with resale value, financed through the owner’s broker and secured on the machines. The $60k is a different problem. MyState doesn’t advertise an overdraft or business loan, and Selfco finances assets rather than cash flow. Better candidates are invoice finance secured on the builder’s progress claims, a short working capital loan, or a revolving business line of credit for repeat gaps.
Splitting the need like this is common. Matching each piece of funding to its job usually costs less than forcing everything into one loan.
Got a mix of asset and cash needs like this? Outline them for us and we’ll suggest how to split it.
Who suits MyState and Selfco?
MyState and Selfco together tend to suit:
- Tasmanian businesses wanting a local bank for everyday transactions and savings;
- businesses anywhere in Australia buying vehicles, plant or equipment through a broker;
- owners who’d like their asset finance with a regulated bank group rather than a finance company.
They’re a weaker fit if you need an unsecured loan, an overdraft, a commercial property loan, or quick cash to cover a tax bill or wages. For those, look further afield.
Questions to ask before you proceed
- Ask your broker: Is Selfco on your panel, and how does its offer compare with two other equipment lenders for this asset?
- Adding establishment fees and any balloon, how many dollars will this cost me from start to finish?
- Will Selfco need a director’s guarantee, and does it take security over anything beyond the asset?
- If a big job pays early and I clear the finance ahead of schedule, what’s the payout charge?
- For MyState: if I bank with you, will you consider any business lending outside Selfco?
If MyState can’t help, you’re in the right place
MyState is a well-run bank, and for Tasmanian businesses its local service is genuinely valuable. Where it doesn’t offer the product you need, the gap is easy to fill:
- Need working capital or a cash buffer? Start with unsecured business loans, which many online lenders assess on bank statements alone.
- Want to borrow against property? Look at home equity business loans or a second mortgage.
- Declined elsewhere too? Our declined by the bank guide maps out next steps.
- Staying local? See business loans in Tasmania, Hobart and Launceston.
- Prefer another customer-focused bank? Read our profiles of Bendigo Bank and Beyond Bank.
Need the part of the loan MyState doesn’t do?
Most businesses that come to us from a regional bank aren’t in trouble. They’ve simply asked for something their bank doesn’t make.
Our form is quick, around sixty seconds, and asking us has no effect on your credit standing. Your details aren’t broadcast to a queue of lenders hoping for a sale. An experienced person reviews your situation and phones you to discuss options. Please be precise about the amount, the purpose and any existing finance, so our first recommendation actually fits.
Frequently asked questions
Does MyState Bank offer business loans?
Not as a general product on its own website. As at October 2026, MyState Bank's business section offers an Everyday Business account, a Business Online Saver and business term deposits. The group lends to businesses mainly through Selfco, its vehicle and equipment finance division.
What is Selfco and how is it connected to MyState?
Selfco is a business vehicle and equipment finance company established in 2003. Its website says it is a division of MyState Bank Limited, which is wholly owned by MyState Limited. It finances equipment, machinery and vehicles used in business.
Can I apply to Selfco directly?
Selfco originates its loans through a national network of accredited finance brokers and sits on most aggregator panels. It does list a phone number and email for general enquiries, but the usual route is through a broker.
Can a business outside Tasmania open a MyState business account?
MyState says its Everyday Business account is only available to businesses based in Tasmania. Selfco's equipment finance, by contrast, is offered nationally through brokers.
Is Auswide Bank part of MyState?
Yes. MyState acquired Auswide Bank in February 2025, and Auswide Bank's website now describes it as a division of MyState Bank Limited. Its business offering is also centred on accounts rather than loans.
Where can a Tasmanian business get a loan if MyState can't help?
Other banks with business lending teams operate in Tasmania, and non-bank, private and online lenders lend statewide. The right one depends on whether you need equipment, working capital or property-backed funds. You can enquire with us without a credit check.