Quick answer
Independent hardware stores usually borrow to carry builders' trade accounts, stock timber and building supplies, buy forklifts and delivery trucks, and refit or expand the store. Invoice finance or a line of credit suits slow-paying trade customers, equipment finance suits the yard and fleet, and property-secured loans suit buying a store or freehold. Banks lend to established hardware businesses; non-bank lenders help when growth or timing outpaces the bank.
Key points
- A hardware store with a trade desk is really two businesses: a cash retail counter and a credit business lending to builders on 30-day or longer terms
- A healthy trade debtor ledger can support invoice finance, turning money owed by builders into cash well before they pay
- Registering your retention of title on the PPSR protects goods you sell on account; unregistered, you're an unsecured creditor if a builder fails
- Trade sales follow the building cycle, so lenders often look at local building approvals and your exposure to a handful of big builders
Walk through the front door of an independent hardware store and you see a retail shop: paint, garden supplies, tools, fasteners, a counter with an EFTPOS terminal. Walk round the back to the yard and the trade desk and you see something else entirely: pallets of timber and sheet products, a forklift, a truck being loaded for site delivery, and a stack of trade accounts with builders who will pay at the end of next month, if you’re lucky.
Those two halves behave very differently, and lenders treat them differently. Getting finance right for a hardware business mostly means funding each half for what it is.
Retail counter or trade desk: which one drives your cash flow?
The retail counter takes cash and card payments on the spot. It’s seasonal, with a strong spring and summer for garden and outdoor lines, and a good Saturday can carry the week. Cash flow is immediate, and margins are generally better than on trade sales.
The trade desk sells in bulk at trade pricing to builders, renovators, plumbers, electricians and other contractors, usually on account. Common terms are 30 days from the end of the month, which in practice means you might wait 45 to 60 days, longer with slow payers. Volumes are bigger, margins tighter, and you’re effectively lending to your customers.
Here’s why it matters: a store doing $4m a year, half of it trade, might easily have $300k to $500k owed to it at any time. Your own cash has already gone out on the materials and the wages behind those sales long before the builders settle up. The more your trade side grows, the more working capital it eats.
What do hardware stores borrow for?
- Funding the trade ledger. Invoice finance advances a large part of each approved trade invoice, so growth in trade sales doesn’t starve the business of cash. It suits stores whose customers are established builders with a record of paying.
- Stock. Timber, steel, sheet products, landscaping supplies and seasonal lines tie up cash in the yard. Bulk buys when suppliers run a deal sit comfortably on a business line of credit, drawn as needed.
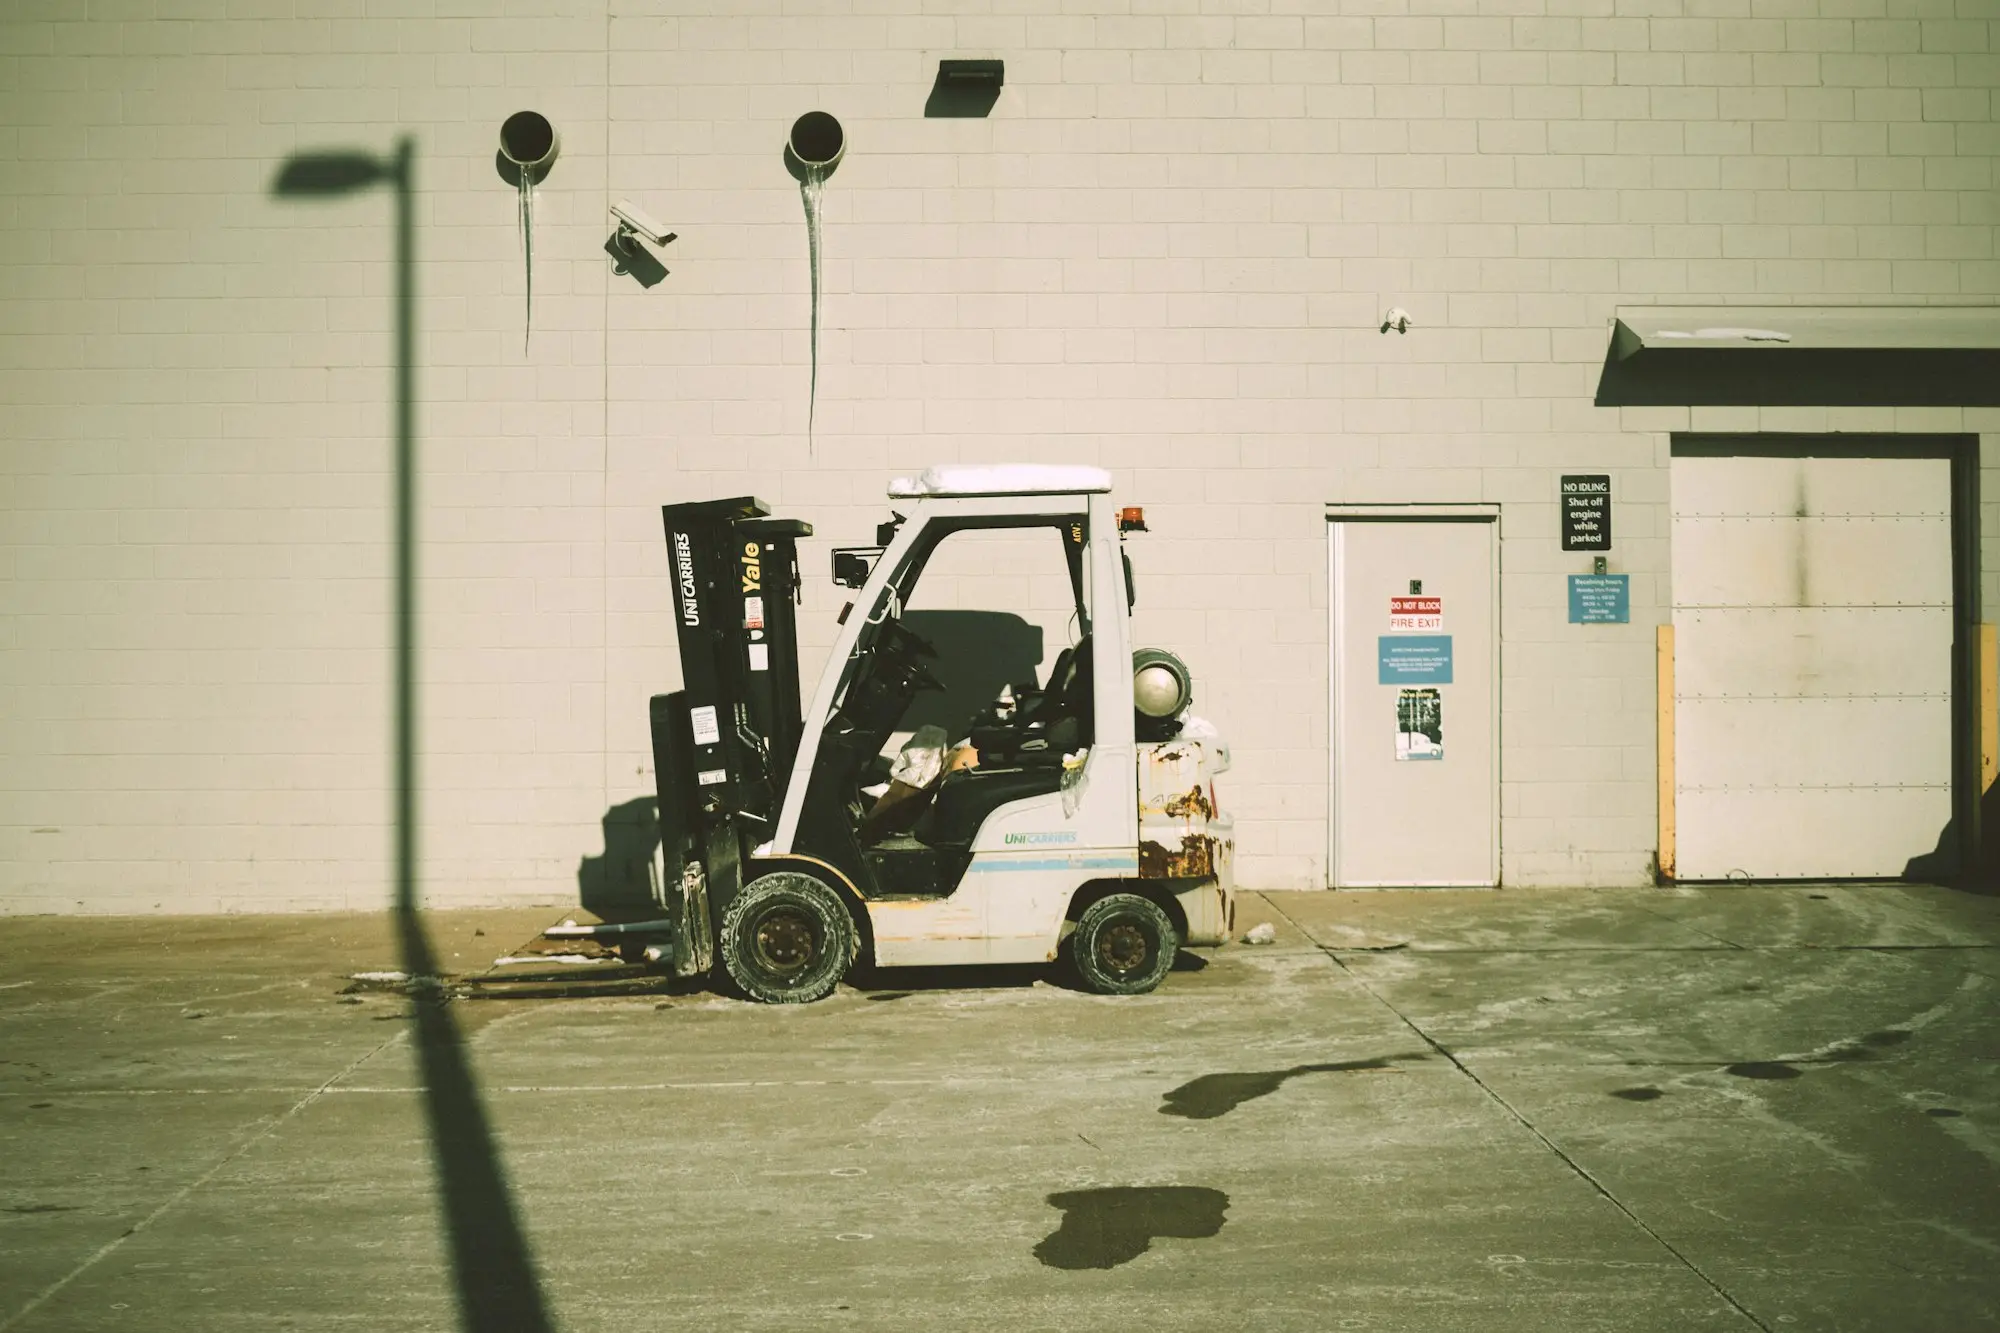
- Forklifts, trucks and yard equipment. Crane trucks, flatbeds, forklifts, saws and racking. Equipment finance or a chattel mortgage, with the equipment as security, is usually the lowest-cost route.
- Refits and expansion. A new trade centre, a drive-through timber yard, a bigger garden centre, or a move to new premises. Larger sums, often funded with property security.
- Buying a store or the freehold. Hardware businesses on owner-occupied land sometimes come with the chance to buy the freehold. A commercial property loan can sit alongside the business purchase.
Our invoice finance calculator gives a quick idea of how much of your trade ledger could be released and what it would cost in dollars over a typical month.
How do lenders assess a hardware business?
Established hardware stores with a few years of good profit, a sound trade ledger and freehold or home equity are exactly what banks like. If your bank is keen, it will usually offer the cheapest finance available, and its offer deserves careful consideration.
When the bank can’t help, or can’t move as quickly as a stock deal or acquisition requires, non-bank lenders look at:
- The aged debtors report. The total outstanding, which accounts it sits with, and how overdue each one is. A ledger full of long-standing local builders paying within 60 days is very fundable. One where a few accounts are 120 days overdue raises questions.
- Concentration. If one or two builders account for a big slice of trade sales, expect questions about how long you’ve supplied them and what happens if one of them falls over.
- Your credit control. Credit applications, account limits, personal guarantees from company directors, and PPSR registrations. Strong credit control lowers the risk of the very ledger a lender is financing.
- Stock management. Accurate stock figures and sensible stock turn. Dead stock in the yard is a cost, not an asset.
- Your banner or buying group. Many independents belong to a buying group or trade under a banner. Metcash, for example, says it merged its Independent Hardware Group with Total Tools in June 2025. Lenders may ask how your supplier terms work and what happens if they change.
Is your bank taking its time on a stock deal or a new truck? Send a quick enquiry and we’ll come back to you with options that suit the timing.
Why PPSR registration matters for a hardware store
If you sell goods on account with a retention of title clause, you keep ownership of those goods until you’re paid. Under the Personal Property Securities Act, that arrangement is generally treated as a security interest, and the PPSR is where you register it.
The PPSR’s own guidance is direct: if you don’t register, you’re left as an unsecured creditor if your customer can’t pay, with a much smaller chance of getting your money or goods back. If you do register correctly, your interest can qualify as a purchase money security interest, which ranks ahead of other secured creditors over those same goods. Timing matters for that priority, so registration should be part of opening a trade account, not something you do after a customer starts paying late. For a repeat customer, one registration can usually cover many supplies.
Lenders financing your trade ledger care about this, because it lowers the chance that a builder’s collapse wipes out what’s owed. It’s worth asking your solicitor or accountant to check your trade terms and registrations, especially if you’ve never reviewed them. Our glossary entry on retention of title explains the term in more detail.
What seasonal and industry risks do lenders consider?
- The building cycle. Trade demand follows housing approvals and renovation activity in your area. When new approvals slow, trade sales usually follow a few months later. The ABS publishes monthly building approvals, and some lenders look at the regional trend.
- Builder failures. When builders go into liquidation, suppliers on unsecured accounts often lose most of what they’re owed. This is the single biggest credit risk for trade-focused stores. Our page on builders’ finance shows the pressures from the other side of the counter.
- Weather. Long wet periods slow building work and garden sales. Bushfire and flood can do both, and leave customers unable to pay for months.
- Big-box competition. National chains compete hard on price for retail and DIY customers. Independents that hold their ground usually do it through trade service, delivery and local knowledge, and lenders like to see that strategy in the numbers.
Documents that make a hardware store application faster
- Aged debtors and aged creditors reports, run on the same day
- A full year of statements from the business account
- Two years of financials, ideally with retail and trade sales shown separately
- Recent BAS and your ATO account statement
- Your standard trade account terms and a sample of PPSR registrations
- Quotes or invoices for any equipment or vehicles
- The lease or title for the premises, and your banner or buying group agreement if relevant
Example: a regional store whose trade side outgrew its bank limit
An invented example. An independent hardware and timber store in regional Victoria turns over about $6m a year, roughly 60% of it trade. Three years of strong local housing growth have pushed trade debtors past $700k, and the bank overdraft is fully drawn most months. A large supplier is offering a better price for a full truckload of frame timber, but the store can’t take the offer without missing the wages run.
The bank is willing to review the overdraft but needs updated valuations and audited figures. In the meantime, the owners set up invoice finance over the trade ledger with a non-bank lender, which advances most of each new trade invoice within a day of it being raised. They tighten trade terms for slow payers, check PPSR registrations on their top 30 accounts, and use the released cash to take the bulk timber deal. The finance cost is a few thousand dollars a month at peak, comfortably covered by the better buying margin and the end of late-fee penalties from their own suppliers.
Funding the next stage of your hardware business
A full yard, a reliable truck, a trade ledger that doesn’t choke cash flow: these are the foundations of a strong independent hardware store, and there’s nearly always a way to fund them. We see plenty of hardware and timber businesses whose bank couldn’t keep pace with how quickly the trade side grew.
Filling in the form is roughly a minute’s work, and your credit history isn’t searched because you asked. Your details aren’t broadcast to every funder in the country. A member of our team reads the whole picture and rings you. Please give honest figures for turnover, trade debtors and the purpose of the funds; it’s the quickest way to land on an option that suits first time round.
Frequently asked questions
Can I use my trade accounts to get finance?
Yes. If your trade customers are established builders and contractors who pay reliably, invoice finance can advance most of the value of their invoices as soon as you issue them. You repay when they pay. Lenders look closely at the age of the ledger and how concentrated it is.
How do I finance a forklift or delivery truck?
Equipment finance or a chattel mortgage is the usual route, with the forklift or truck as security. Lenders are comfortable with recognised brands and models that have a resale market, and used equipment can usually be financed too.
Do I need to register on the PPSR?
If you sell on credit with a retention of title clause, registering that interest on the PPSR is how you protect it. Without registration, you rank as an unsecured creditor if a customer goes into liquidation or bankruptcy, and your chances of getting paid or recovering goods drop sharply.
Can I borrow to buy a hardware store?
Yes. Lenders look at trading history, the split between retail and trade sales, the strength of the trade ledger, the lease or freehold, and your experience. Acquisitions are usually funded with a deposit plus property-secured lending, and sometimes the freehold is bought at the same time.
Does belonging to a banner group help with a loan?
It can. A banner or buying group affects your purchasing terms, marketing support and brand recognition, and lenders often see membership as a sign of a stable business. They may ask to see the agreement and the terms you buy on.
What if a big builder customer goes under?
It can leave a hole in cash flow quickly. Lenders will ask how much of your trade ledger sits with your top few customers. Spreading your trade book, registering on the PPSR and having a line of credit in place all reduce the damage.