Quick answer
Fashion boutiques usually borrow to pay for seasonal indent orders months before the stock sells, to fit out or refresh a store, and to carry stock through slow weeks. A business line of credit or short-term working capital loan suits seasonal buying, equipment or fit-out finance covers the shop itself, and property-secured lending suits bigger moves like a second store. Banks lend to established boutiques with clean books; non-bank lenders assess on bank statements when the bank can't.
Key points
- Boutiques often commit to a season's indent order six months or more before it hits the racks, so the cash gap is built into the business model
- A revolving line of credit usually suits seasonal buying better than a fixed lump sum, because you draw it twice a year and pay it down as stock sells
- Gift cards sold since 1 November 2019 must generally stay redeemable for at least three years, so unredeemed balances are a liability lenders may ask about
- Lenders look hard at sell-through, markdowns and aged stock, because a rack of last season's dresses is worth far less than its cost
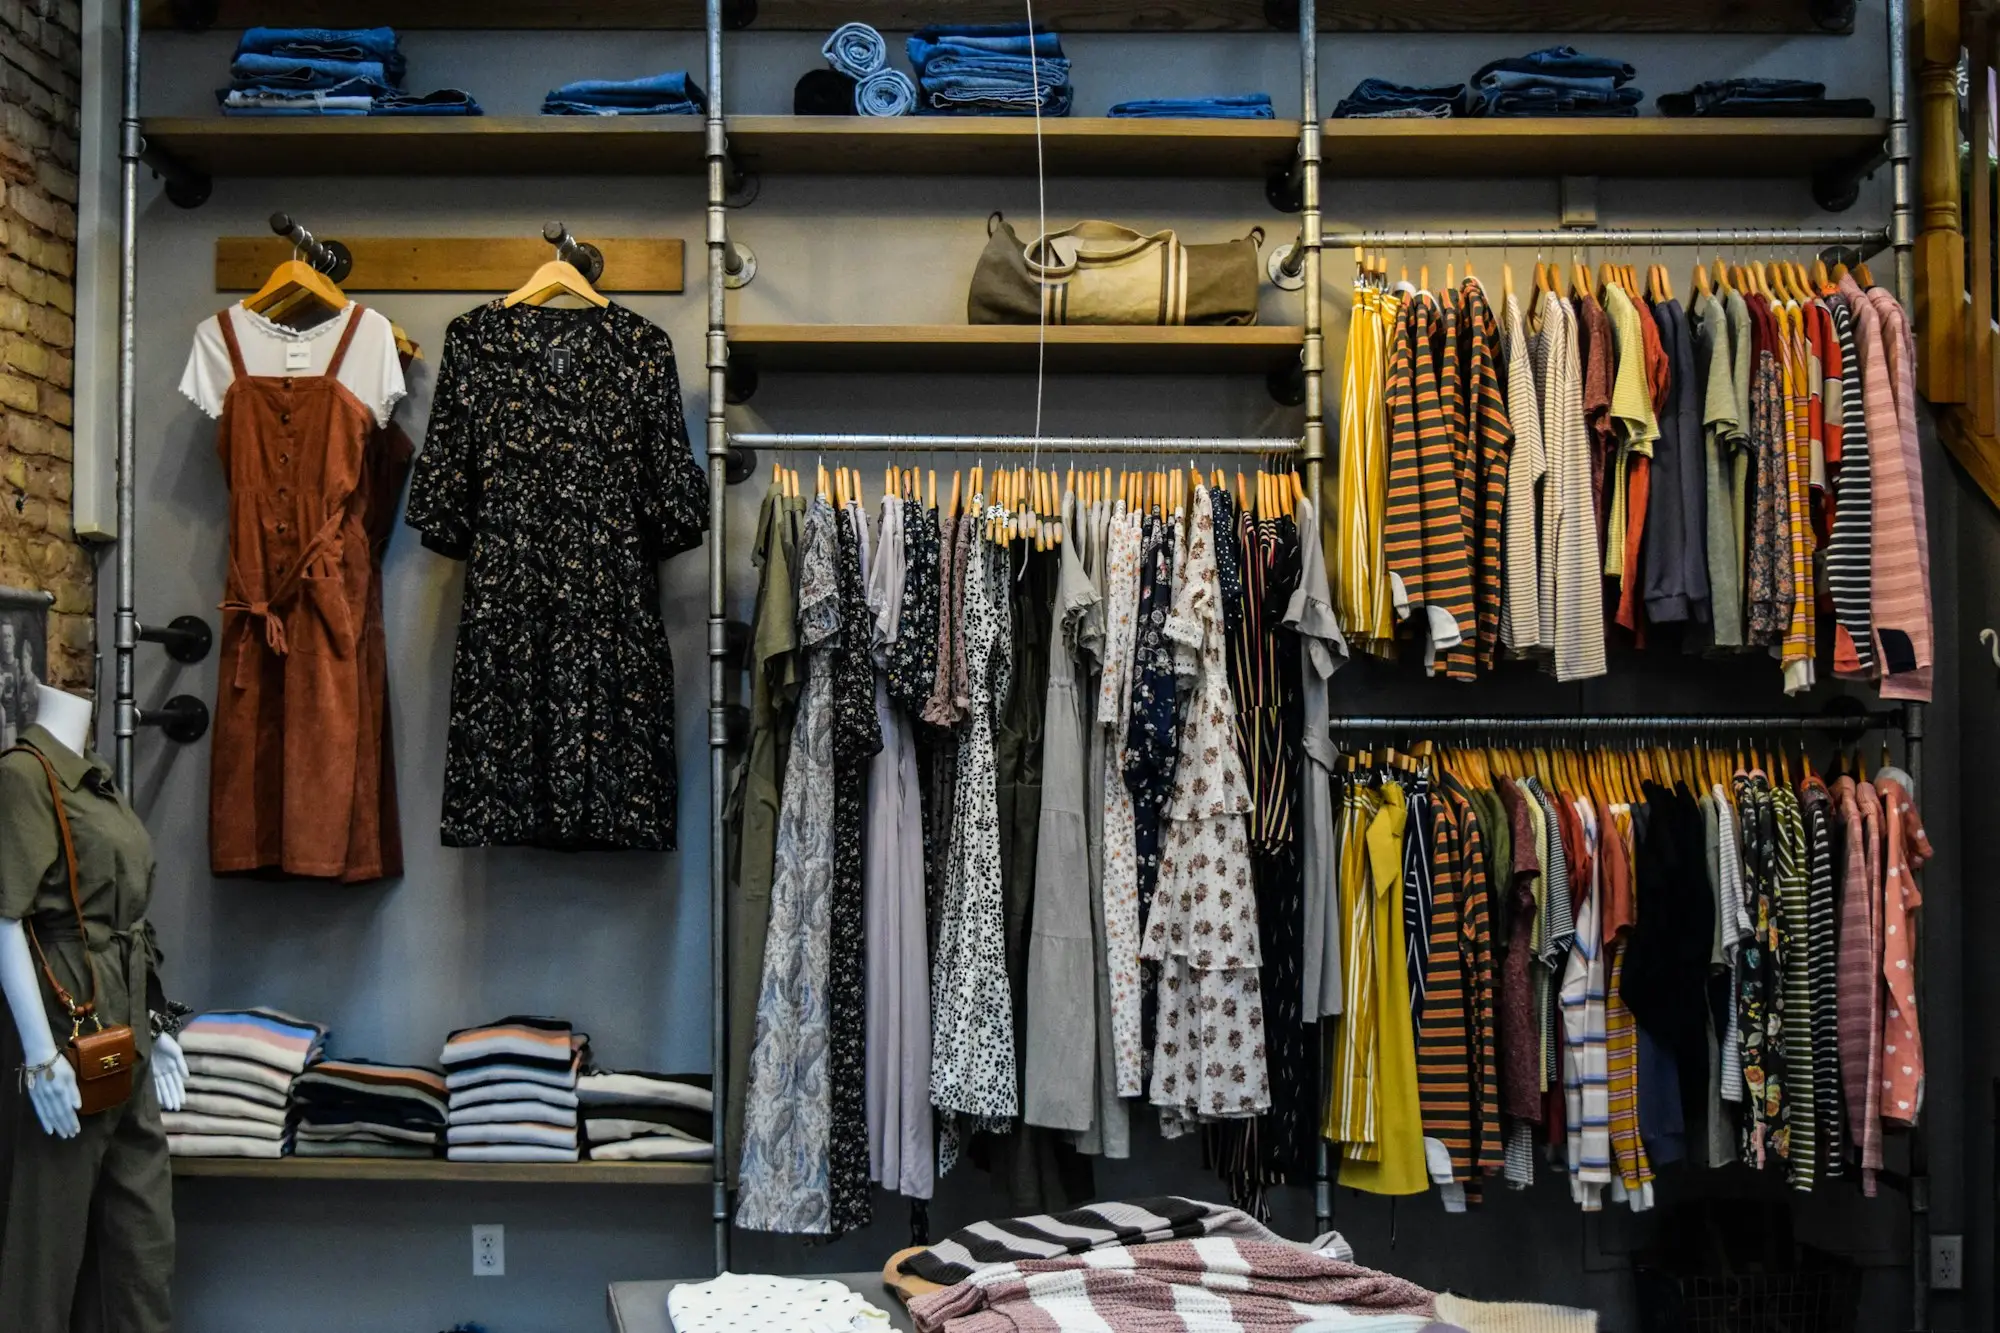
Picture a February afternoon in a boutique. Summer linen is going out the door at 30% off, the shop is quiet, and you’re signing off on the winter knitwear and coats you agreed to back in spring. The money for winter leaves your account before most of the summer stock has sold. That overlap is the single most common reason fashion boutique owners go looking for finance.
It isn’t a sign of trouble. Independent fashion retail runs on buying ahead, and the businesses that handle it well usually have a funding line ready before the order deposits fall due.
Why does a boutique need money before it sells anything?
Most independent boutiques buy in one of three ways, and each has a different cash profile.
- Indent orders. You order from a label or wholesaler’s range at a trade show or showroom, often two seasons ahead. Some suppliers want a deposit when you confirm, with the balance due on delivery or on short trade terms after it.
- In-season or stock-service buying. Smaller top-up buys from what a supplier already holds in its warehouse. Less risk, smaller margins, quicker turnaround.
- Direct imports. Buying straight from overseas makers or agents. Better margins, but you usually pay well before shipping, plus freight, duty and GST at the border, and you wait weeks for the container.
A rough calendar for a boutique buying on indent might look like this:
| When | What’s happening in the shop | What’s happening to cash |
|---|---|---|
| August to October | Spring stock arriving, winter clearance | Paying for spring and summer deliveries; confirming autumn and winter orders |
| November to December | Peak Christmas and party season trade | Strongest takings of the year; best time to pay debt down |
| January to February | Summer sale, post-Christmas slump | Takings soft while autumn deliveries land |
| March to May | Autumn and winter stock selling at full price | Recovering cash; confirming next spring’s orders |
| June to July | End of financial year sales, cold-weather trade | Clearing winter; next season’s deposits and deliveries approaching |
The squeeze points are obvious: late summer and mid-winter, when you’re paying for the next season while marking down the last one. Our seasonal stock funding guide goes deeper on sizing a facility for this pattern.
How do lenders size up a fashion boutique?
A bank is a good first stop for an established boutique with two or more years of profitable trading, tidy financial statements and some property security. Bank money is usually the cheapest you’ll find, so if your bank wants to help, take the offer seriously.
Plenty of good boutiques don’t fit the bank’s boxes, though. Profit on paper may be thin after depreciation and the owner’s wages, the business may be under two years old, or there’s simply no property to offer. Non-bank lenders tend to look at different things:
- Twelve months of bank statements. Steady deposits, a balance that holds up through the slow months and no run of dishonours.
- Seasonality they can understand. A boutique that drops 40% in January every year is fine, as long as it recovers every year. Explain the pattern up front.
- Sell-through and markdowns. How much of each season sells at full price, and how much ends up on the sale rack. A shop that clears 70% at full margin is a very different risk from one that relies on clearance.
- Aged stock. Lenders know fashion stock loses value quickly once the season changes. A big pile of last year’s range can make your balance sheet look healthier than it really is.
- The lease. Remaining term, options, and whether the landlord holds a bank guarantee. A short lease on your best site is a real risk, and lenders will ask.
If your bank’s answer was slow or a flat no, start a quick enquiry here and someone will talk you through what else fits.
Which loan types suit which boutique costs?
Matching the product to the purpose saves real money. A two-year term loan used to pay a ten-week stock bill means paying interest long after the stock has gone.
Seasonal buying: a line of credit. With a business line of credit you can draw for deposits and deliveries, then repay as the season sells. Interest runs only on the drawn amount, and the full limit comes back for the following season once it’s repaid. It’s the closest thing to a natural fit for indent buying.
A one-off stock opportunity: short-term working capital. If a label offers end-of-range stock at a sharp price, or you want to take a larger position in a range that sells well, a working capital loan over six to twelve months can make sense. Run the numbers through our margin and markup calculator first, so you know the margin left after finance costs.
Fit-out and refurbishment. Shelving, racks, lighting, change rooms, signage and point-of-sale gear. Equipment-style finance can cover some of this, and an unsecured or property-secured loan covers the rest. See our shop fit-out funding page for how owners usually split it.
A second store or buying an existing boutique. Larger and longer. Lenders will look at the existing store’s track record, the new lease, and how you’ll staff and stock both. Property-secured lending is common here because the amounts are bigger.
What to be careful with. Daily or weekly repayment products sized on card takings, such as a merchant cash advance, can feel easy in December and painful in February. If you consider one, check how repayments behave when takings fall.
Cash in your account that isn’t really yours yet
Fashion retailers often hold customer money for goods or services they haven’t delivered. Lenders reading your statements may not see the difference, so it pays to understand it yourself.
Gift cards. Under Australian Consumer Law, most gift cards sold from 1 November 2019 must be redeemable for at least three years. Boutiques sell plenty of them in December. That cash arrives months or years before the customer takes the stock, and it shows up as a liability in your accounts. Spending it on next season’s order is common, but count it before you borrow against the same cash flow twice.
Lay-by. Customers who pay off an item over time can generally cancel before they take delivery, and you can only keep a termination charge if it’s in the written agreement and reflects your actual costs. Lay-by deposits are not free working capital.
Buy now pay later. BNPL providers settle to you quickly, minus their merchant fee, so the cash is genuinely yours. The cost is the fee, which comes off your margin on every sale. Factor it in when you price.
What risks do lenders weigh in fashion retail?
- Weather. A warm May or a cold, wet December can strand a season’s stock. Lenders know this and look for owners who’ve managed bad seasons before.
- Label concentration. If one label provides half your sales and it opens its own store nearby or starts selling direct online, your business changes overnight.
- Online competition. Lenders are more comfortable with boutiques that also sell online or through social media, because it shows a second channel. Our page on online store and ecommerce finance covers that side.
- Foot traffic and the lease. Shopping strip vacancies, centre redevelopments and rent reviews all affect the business’s future. A lender may ask about your lease term relative to the loan term.
What should you have ready?
- A year of statements for each business account your takings land in
- Your latest BAS lodgements and a current ATO statement
- Your profit and loss and balance sheet, ideally with a stock figure you’re confident in
- Supplier order confirmations or invoices for the season you’re funding
- A copy of the shop lease, including options and any bank guarantee arrangements
- Sales by season for the last two years, with full-price versus markdown split if your point-of-sale system can produce it
Example: a boutique funding winter while summer is still on the racks
An invented example to show how it can work. A women’s fashion boutique on a busy strip in inner Brisbane turns over around $900k a year across the shop and its website. Each spring the owner confirms an autumn and winter order of about $140k across six labels, with deposits due on confirmation and the balances due as stock lands from February.
The business is profitable, but the January slump means the account runs low just as the first winter deliveries arrive. The bank is open to helping but wants this year’s financials first, and the accountant won’t have them done for two months.
Instead, the owner arranges a $100k line of credit with a non-bank lender, assessed on twelve months of bank statements and the order confirmations. She draws about $70k in February and March, pays it down through April and May as coats and knits sell at full price, and finishes June with the balance close to zero. The total interest and fees over the season come to a few thousand dollars, less than the margin on the extra stock she was able to take. Next spring the bank conversation starts with a cleaner set of figures.
Talk to someone about your boutique’s next season
Indent orders, a refreshed fit-out, a second store or just breathing room through February: every one of these has a sensible way to fund it, and you don’t need a perfect set of accounts to find out what that is. We regularly hear from fashion retailers whose bank couldn’t move in time.
Our form is short, about sixty seconds of your time, and filling it in doesn’t leave a mark on your credit file. We keep your details in-house; nobody forwards them to a queue of finance companies. One of our team reads your situation personally and rings you. Give us your real turnover, the size of the next order and its due date, because honest numbers let us point you to a workable option on the first call.
Frequently asked questions
Can I get a loan to pay for my next season's indent order?
Yes. Most boutiques use a business line of credit or a short-term working capital loan for this. Lenders will want to see your bank statements, how previous seasons sold, and the order confirmation or supplier invoice showing the amount and delivery window.
Is stock enough security for a boutique loan?
Usually not on its own. Fashion stock loses value quickly once a season passes, so lenders rarely lend much against it. Most boutique lending is either unsecured, sized on turnover and cash flow, or secured over property if you have it.
How much can a small boutique borrow unsecured?
It depends mainly on turnover, how long you've traded and how your bank account behaves. Unsecured lenders typically work in the range of $5k to $500k across all industries, and a boutique would normally sit at the lower end unless turnover is substantial.
Will lenders count my afterpay or card terminal settlements as income?
Yes. Settlements from card terminals and buy now pay later providers show up as deposits in your business account, and lenders reading bank statements treat them as sales. Keeping all takings flowing through one business account makes this much easier to assess.
Can I borrow to open a second boutique?
Yes, but lenders will want to see that the first store is consistently profitable and that you can manage stock across two sites. A second location is often funded with a mix of savings, a fit-out loan and sometimes property-secured finance.
My bank declined me. What now?
Ask the bank why, because the reason points to the fix. If it was trading history, low profit on paper or no property, non-bank lenders that assess on bank statements are the usual next step, and they move faster.