Quick answer
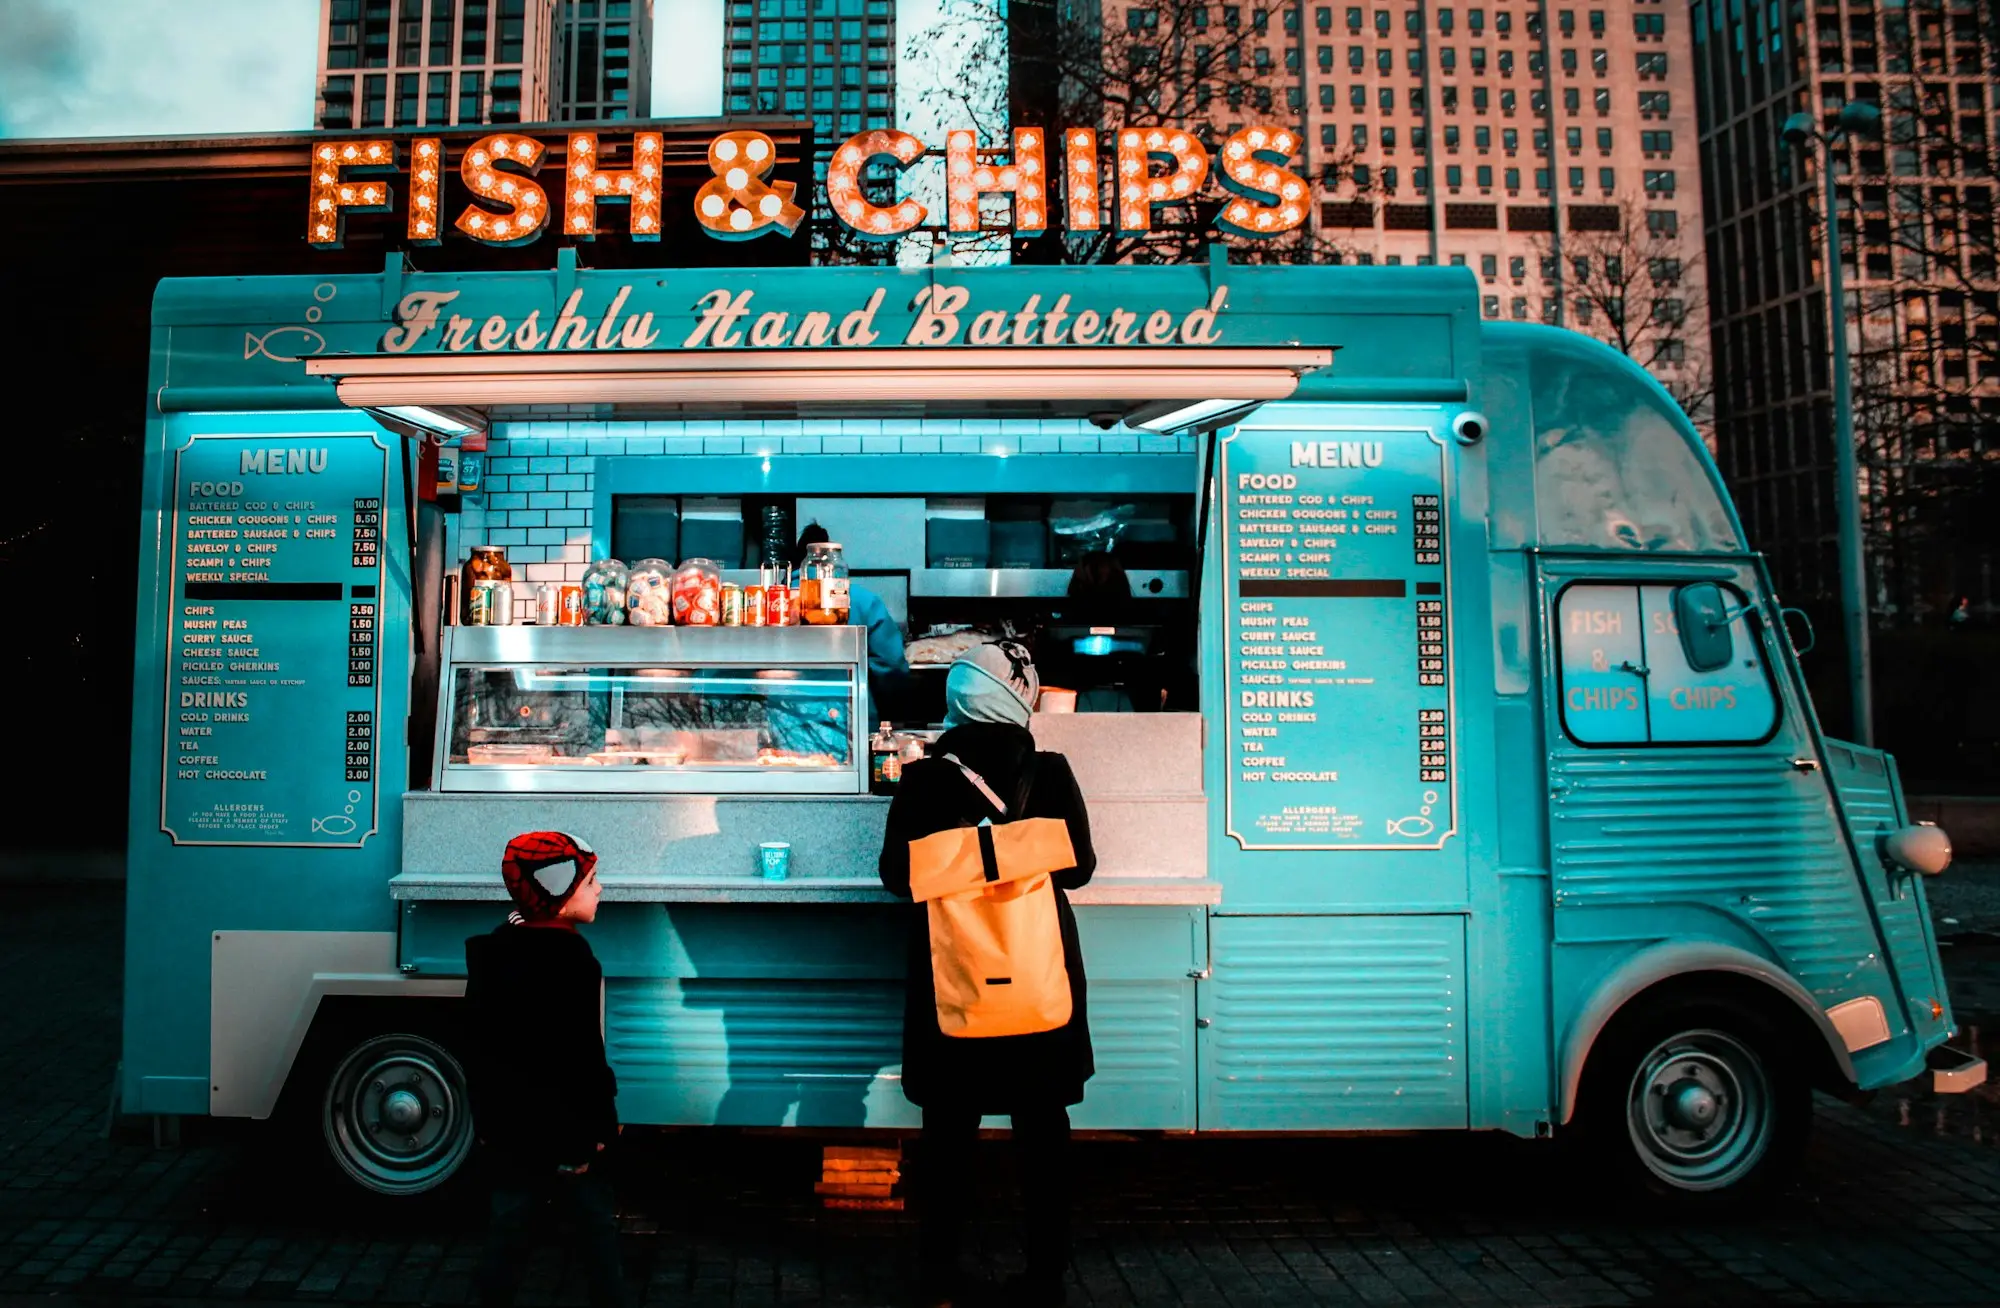
Food truck owners usually borrow to buy or build the truck or trailer, fit out the kitchen, and cover event fees and stock before the season starts. A registered, roadworthy vehicle can often be financed with a chattel mortgage or equipment finance, secured by the vehicle. Custom builds and brand-new operators are harder, so lenders may want a deposit, a director guarantee or property security. Established trucks can also use unsecured loans sized on card takings.
Key points
- A registered truck or van is usually easier to finance than a trailer, and both are easier than a one-off custom build
- Builders often want staged payments before the unit exists, which most asset lenders won't fund until delivery
- In Victoria, mobile food businesses register once through FoodTrader with a principal council; in NSW, approval can be needed in each council area you trade in
- Event site fees, stock and staff are paid up front, so the first season needs working capital as well as the truck
A food truck looks like a simple deal for a lender: there’s a vehicle, it has wheels, it can be sold. In practice it’s a little more complicated. The value is split between a chassis that lenders understand well and a fitted kitchen they understand far less, and many operators are new to running their own business. Knowing how lenders weigh those pieces helps you put forward an application that gets funded.
Truck, van, trailer or custom build: how do lenders see each?
| Unit | How lenders usually treat it | What to expect |
|---|---|---|
| Registered truck or van, already fitted | A vehicle with a fit-out, valued on make, model, age and kilometres | Often financed with a chattel mortgage, with the vehicle as security |
| Food trailer | Lower purchase price, but most of the value sits in the kitchen | Some equipment lenders fund it; others want a larger deposit |
| Bare vehicle plus a new fit-out | The vehicle is easy; the fit-out is a separate question | The vehicle may be financed, with the fit-out funded another way |
| One-off custom build | Hard to value until finished, with a thin resale market | Usually funded only on delivery, often with a deposit or other security |
The big catch with custom builds is timing. Builders commonly ask for a deposit and staged payments while the unit is being made. Most asset lenders won’t release funds until the finished truck or trailer is delivered and their security can be registered on the PPSR. So you may need to fund the build stages yourself, then refinance once it’s delivered, or use a separate loan to bridge the gap.
Our page on commercial vehicle finance explains the vehicle side in more depth, and chattels covers why moveable assets are treated the way they are.
What makes food trucks a harder ask for some lenders?
None of these are deal-breakers, but they explain why a lender might ask for more.
- Short trading histories. Many operators are in their first or second year. Most cash flow lenders want somewhere between half a year and a full year of takings on record before they’ll lend on turnover alone.
- Seasonal income. Festival and market season can carry the year, while winter can be thin. Lenders look at the weakest months, not the best.
- Mobile premises. There’s no fixed site, no lease and no landlord, so the business can be harder to assess than a shopfront.
- Card and cash mix. If a lot of your income is cash, it may not show up clearly on bank statements. Bank your takings consistently so lenders can see them.
If you’re under a year in, our page on new business loans with an ABN under 12 months explains what lenders realistically offer.
Do council approvals matter to a lender?
A lender won’t assess your food safety plan, but it may ask where and how you’ll trade. It wants to know the truck will actually be allowed to operate and earn.
Victoria has a statewide system. Mobile and temporary food premises register through FoodTrader with a principal council, usually the one where the food is prepared, stored or the vehicle is garaged. That registration lets you trade across the state, though you lodge a statement of trade before each event or site, and separate permission is needed for council land or footpaths.
New South Wales works council by council. The NSW Food Authority’s guidelines for mobile food vending vehicles set the food safety rules, while local councils handle approvals and fees. Depending on where you plan to sell, you may need consent from more than one council.
Other states have their own arrangements, generally run through local councils. Getting registration sorted before you buy the truck avoids paying for a vehicle you can’t yet use.
What does a first season really cost?
The truck is the headline number, but it’s not the whole bill. Before the first customer pays you, expect to fund some combination of:
- Site and event fees, often paid weeks or months before the event
- Opening stock, packaging and gas
- Council registration and food safety supervisor training
- Insurance, vehicle registration and a generator if the truck needs one
- Wages for help on busy days
- A payment terminal and point-of-sale setup
A good rule is to work out how many weeks of costs you could cover if the first month is slower than you hope. Our cash runway calculator gives you that figure, and the break-even calculator shows how many sales a week the truck needs to cover its costs, including loan repayments.
Weighing up a truck or a fit-out? Get a feel for your options. It’s around a minute online, with no credit check just for enquiring.
Which finance fits which food truck need?
- Buying a fitted truck or van: a chattel mortgage or equipment loan. Read funding for buying vehicles for more.
- Kitchen equipment for a new build: equipment finance for items with resale value, such as fridges, fryers and griddles.
- Build deposits and progress payments: a short unsecured business loan for established operators, or a property-secured loan if you own a home with equity.
- Event fees and stock for the season: a business line of credit suits this because you draw only when you need to.
- Expanding to a second truck: often easiest once the first truck has a solid year of takings to show.
Banks can be a good fit if you have an established business, a solid personal credit history and property to offer, and their total cost is often the lowest. If the bank says no because the business is new or seasonal, non-bank asset lenders and unsecured lenders look at different evidence.
What should a food truck owner have ready?
Start with recent statements for the account your takings land in, plus your most recent activity statement where you lodge one. Add the vehicle or trailer details (or the builder’s quote and build specification), your council registration or approval, a list of booked events or regular sites, and your driver’s licence and ABN. Owners who also hold a job or other income should include evidence of that too, because it can strengthen a new-business application.
Worked example: a second-year operator upgrading
Fictional figures, for illustration only. A Melbourne operator has run a converted van for 18 months, mainly at weekend markets and corporate lunches. Card takings average $14k a month in summer and $6k in winter. They want to move into a larger, purpose-built truck costing $135k to handle festivals.
The builder wants $40k up front and the balance on delivery. The operator pays the deposit from savings and a small unsecured loan, then finances the $95k balance through a chattel mortgage when the truck is delivered and registered. The old van is sold for $38k, which clears the unsecured loan early. Before signing, the operator checks the repayments against the winter months, not just the summer ones, and books three regular weekday corporate sites to steady the quiet season.
Planning the next step for your truck?
A food truck can be a fantastic small business, and good finance is mostly about timing: funding the build at the right stage and keeping enough cash for the first season.
Sketch out the plan for us in the enquiry form. The form takes roughly a minute and doesn’t lead to a credit enquiry. Your details aren’t distributed across the market, so there’s no barrage of calls from funders you’ve never heard of. Instead, someone who looks at vehicle and hospitality finance reads your enquiry and rings you. Accurate figures on takings, the truck’s price and your timing help us find the right path first time.
Frequently asked questions
Can I get finance for a food truck with no trading history?
It's possible, but harder. Asset lenders may fund a new operator if the truck is a recognisable vehicle with resale value and you put in a meaningful deposit. Without trading history, lenders lean on your credit file, hospitality experience, other income and any property you own. Expect more questions and a smaller loan than an established operator would get.
Is a food trailer easier or harder to finance than a truck?
Usually a little harder. A registered truck or van has a clear market value and an engine and chassis lenders understand. Trailers are cheaper to buy, but their value sits mostly in the fit-out, which is harder to resell. Some equipment lenders fund both, so ask early.
Will a lender pay the builder before the truck is finished?
Most asset lenders only pay out once the finished unit is delivered and they can register their security. If your builder wants deposits and progress payments during the build, you'll usually need to fund those yourself, or use a separate unsecured or property-secured loan.
Do I need council approval before applying for a loan?
Not necessarily before applying, but a lender may ask how and where you plan to trade. In Victoria, mobile food premises register through the statewide FoodTrader system. In NSW, councils approve mobile food vending and you may need consent from each council area you trade in. Having that plan worked out helps your application.
Can a food truck get an unsecured business loan?
Yes, once it has been trading for a while. Many unsecured lenders want six to twelve months of business bank statements showing regular takings. Repayments are sized on those takings, so seasonal swings matter.
What happens to the loan in winter?
Repayments on a fixed loan don't stop when events dry up. Plan for the quiet months before you borrow, either by building a cash buffer in summer or choosing a structure with flexible drawdowns, such as a line of credit, for working capital.