Quick answer
A security interest is a legal right over an asset that secures payment of a debt or performance of an obligation. In Australia, security interests over personal property (anything other than land) are governed by the Personal Property Securities Act 2009 and recorded on the national PPSR. Interests over land are recorded separately as mortgages or caveats at the state land registry.
Key points
- Covers any arrangement that in substance secures a debt, whatever it's called
- Personal property goes on the PPSR; land goes on the state title register
- Registration order usually decides who gets paid first
- A late or wrong registration can leave a lender unsecured if the borrower fails
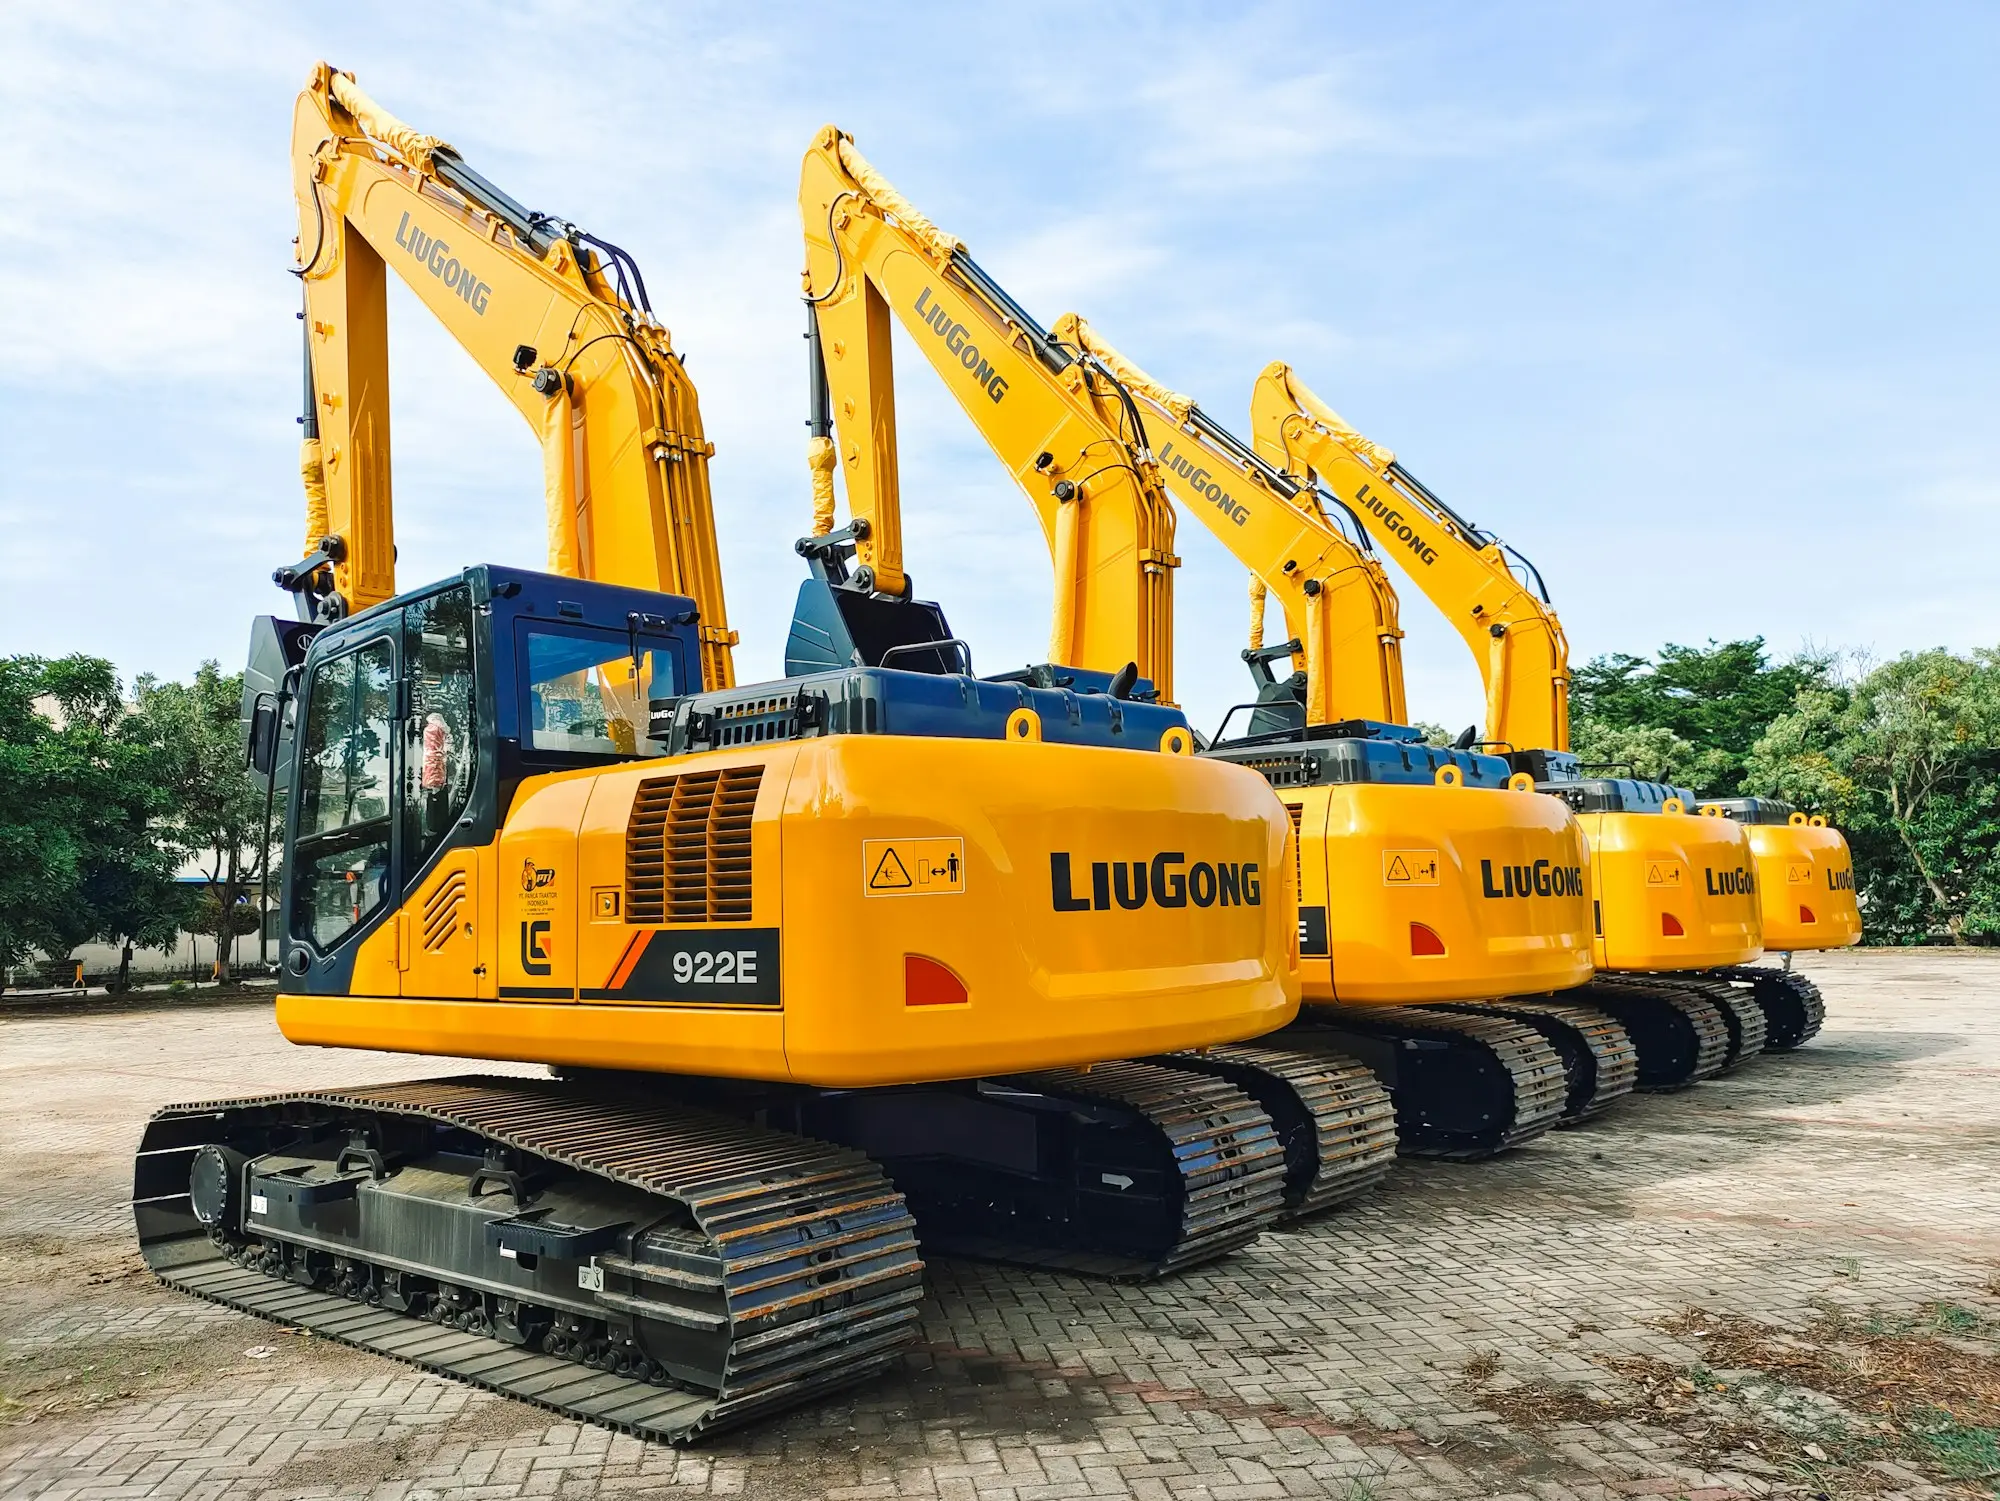
Picture a used excavator advertised for $95k on a trade site. The seller owns it outright, or says so. A security interest is what could make that claim false: a lender’s legal right over the machine, granted to secure a loan, that follows the asset even after it changes hands. Knowing how these interests work protects you whether you’re borrowing, lending or buying.
The PPSA: one test for every kind of security
Before 2012, Australia had a patchwork of state and federal registers for charges, bills of sale and vehicle encumbrances. The Personal Property Securities Act 2009 replaced most of them with one national law and one register, the PPSR, which went live in January 2012.
The Act’s key idea is substance over form. Section 12 defines a security interest as an interest in personal property that in substance secures payment or performance of an obligation. The label on the document doesn’t matter. A chattel mortgage, a general security agreement, a hire purchase arrangement and a supplier’s retention of title clause are all security interests if they function as security. Certain leases of goods for more than a year are caught as well.
“Personal property” means almost anything except land: vehicles, equipment, stock, receivables, intellectual property, even crops and livestock. Land is left to each state’s title register, where lenders record mortgages and caveats.
Attachment, perfection and priority
Three words do most of the work in this area.
| Step | What it means | Why the borrower should care |
|---|---|---|
| Attachment | The interest exists between lender and borrower once there’s a signed agreement and the borrower has rights in the asset | The lender can enforce against you |
| Perfection | Usually achieved by registering on the PPSR | The lender’s claim now holds up against third parties |
| Priority | Where two interests cover the same asset, the earlier perfected one generally wins | Decides who is paid first in a default |
A special rule helps suppliers and equipment financiers. A purchase money security interest, which secures the price of the specific goods being bought, can jump ahead of an earlier general security agreement if it’s registered on time. For inventory, that means registering before the buyer gets possession; for other goods, within 15 business days.
Why registration timing is a big deal
Under the Corporations Act, a security interest that isn’t registered within 20 business days of the agreement can vest in the company if it enters liquidation, administration or a deed of company arrangement within six months of a late registration. In plain terms, the lender’s security disappears and it ranks as an unsecured creditor.
That rule explains why lenders are fussy about details. A registration with the wrong ACN or a misspelt company name can be treated as ineffective. If a lender asks you to confirm your exact legal entity name, it isn’t being pedantic.
Example: the second-hand excavator
A civil contractor in Toowoomba agrees to buy that $95k excavator from another operator. Before paying, they search the PPSR by serial number and find a registration by an equipment financier against the seller’s company.
The contractor asks the seller to have the financier confirm the payout figure. At settlement, part of the purchase price goes straight to the financier, which removes its registration, and the balance goes to the seller. The contractor ends up with clear title. Had they skipped the search, the financier could have repossessed the machine from them.
If you’re financing a machine like this, the equipment finance and chattel mortgage pages explain how your own lender’s interest will be set up. Or start an enquiry and we’ll walk you through it.
Related terms
PPSR, personal property, security, secured creditor and floating charge.
Borrowing against equipment, stock or receivables?
Almost every business loan short of a pure unsecured facility creates a security interest somewhere, and lenders will search the PPSR against your business as part of their checks. Existing registrations aren’t necessarily a problem; they just need to be explained.
Tell us what you’re looking to fund. The form is quick, roughly a minute, and your credit history stays exactly as it was. We won’t scatter your application across the market. A real member of our team reviews it and phones you to discuss the structure. Mention any finance already secured over your assets so the lender we line up is comfortable with it from day one.
Frequently asked questions
What counts as a security interest under the PPSA?
Any interest in personal property that in substance secures payment or performance of an obligation, regardless of the form of the document. Chattel mortgages, general security agreements and retention of title clauses all qualify. Some longer leases and commercial consignments are treated as security interests too.
How do I check whether an asset has a security interest on it?
Search the PPSR. Vehicles and some other goods can be searched by serial number, such as the VIN, and businesses can be searched by ABN or ACN to see registrations against them. Do this before buying a used vehicle, machine or business.
What happens to a security interest when the loan is paid off?
The lender should end its PPSR registration. If it doesn't, the grantor can ask it to remove the registration, and the PPSR has a process to demand removal of a registration that shouldn't be there.
Does a security interest cover property such as my house?
Not under the PPSA. Land and buildings are excluded. A lender's interest in real property is recorded on the title at the state land registry, usually as a registered mortgage or a caveat.
Why did my supplier register against my business on the PPSR?
Suppliers that sell on retention of title terms often register so they can reclaim unpaid goods if your business fails. It's routine and doesn't mean you've done anything wrong, but lenders will see it on a search.